Posted on Leave a comment

From US$79,300 to US$82,400: Mapping the narrow corridor that decides Bitcoin’s September

I see an intricate interplay of global economic forces and internal trading mechanics. Bitcoin recently advanced 0.56 per cent to reach US$80,347.18 over a single day. This specific valuation increase closely tracks the broader sector’s expansion of 0.84 per cent. Total capitalisation across the entire speculative token landscape climbed 0.61 per cent to hit US$2.72T.

Investors currently treat these virtual commodities as highly sensitive economic indicators rather than isolated betting vehicles. Traditional financial benchmarks heavily dictate daily fluctuations. The primary engine propelling this upward momentum stems directly from widespread equity beta.

Participants actively price in persistent geopolitical friction and shifting central bank policies. Heightened tensions between the United States and Iran continue pushing global energy costs higher. Simultaneously, a tight Federal Reserve stance, following robust employment figures, forces Wall Street to recalibrate risk models. These exact elements heavily impact all speculative instruments globally.

Bitcoin currently exhibits a striking 92 per cent correlation with the S&P 500 index. This high statistical overlap clearly indicates a rate-sensitive and broad economic movement. The digital token essentially trades as a traditional risk instrument right now. Short-term valuation direction relies heavily on Wall Street sentiment and shifting liquidity expectations.

Institutional participants provide a massive underlying floor for current valuations. Exchange-traded funds focusing on digital commodities raked in nearly US$1B in net inflows just last week. This massive influx of traditional capital provides undeniable structural support for current pricing tiers.

Investors must now watch the upcoming United States Consumer Price Index report scheduled for September 11. This inflation data release will heavily influence central bank rate expectations and dictate future volatility. Participants eagerly await this data point to confirm whether the current bullish momentum has long-term staying power or is merely a temporary reflexive bounce. Gold also shares a 74 per cent correlation with the virtual coin, showing that safe-haven narratives occasionally blend with risk-on behaviour during uncertain times. Internal trading mechanics significantly amplified the initial broad-based economic upturn.

Liquidations for the top digital asset surged an astonishing 151 per cent to reach US$20.14M within a single day. This spike in forced selling primarily originated from bearish positions. Such an increase in forced closures creates intense reflexive buying pressure. Speculators who bet against the sector must quickly buy the underlying instrument to cover their losing wagers. This mandatory buying activity significantly amplifies the initial upward move and creates a cascading effect across order books.

Also Read: Bitcoin just broke US$81,000: The real reason is not what you think

The underlying derivatives structure presented perfect conditions for a classic squeeze. The modest broad economic rise simply triggered a massive cascade of buy orders from heavily leveraged entities. My analysis shows that the internal plumbing of the futures ecosystem often dictates daily volatility far more than fundamental news. Speculators utilising high leverage inject immense fuel into the rally, but they simultaneously increase the risk of sharp corrections. Total open interest recently climbed by 4.8 per cent, while the average funding rate jumped by 44 per cent in a single day. These metrics indicate aggressive positioning.

Market makers observe these shifting derivatives metrics to gauge underlying retail enthusiasm and institutional hedging activity. Capital is actively rotating out of the largest digital token and flowing into high-momentum alternative projects. The Altcoin Season Index jumped 56 per cent on a weekly basis to reach a reading of 42. This metric signals that speculators aggressively chase momentum in specific niche narratives.

Privacy tokens and meme coins currently lead this speculative charge. Zcash recently surged 21 per cent to reach US$1,237. This project benefits greatly from a Grayscale exchange-traded fund tailwind and a simultaneous short squeeze. The Social Money category also experienced a massive rocket upward, climbing 63 per cent in a short period.

Dominance of the premier cryptocurrency recently dipped to 59.11 per cent as participants seek outsized returns in smaller ventures. Speculators are actively betting on these sectors while the largest digital asset consolidates its recent gains. Sustained strength in the seasonal index above 50 would definitively confirm a broader alternative token season. Entities must closely watch for a sharp reversal in funding rates from positive to negative. Such a sudden shift would likely signal a sentiment peak and prompt widespread profit-taking.

A benign legal backdrop continues to support institutional confidence in these speculative arenas. Clear commodity classifications established by federal regulators in March 2026 provide a stable framework for large capital allocators. This clarity removes uncertainty and encourages traditional institutions to increase exposure to virtual assets.

Also Read: Bitcoin slipped below US$80,000, so why are traders still betting on US$82,000?

The immediate pricing path heavily hinges on specific technical thresholds and upcoming events. The premier cryptocurrency must successfully hold the critical support zone between US$79,300 and US$79,900. This band encompasses the 50 per cent Fibonacci retracement threshold and the seven-day moving average. Immediate resistance currently sits between US$81,000 and US$82,400. Another barrier rests precisely at US$81,259. Traders view this specific price point as a major psychological hurdle that requires substantial buying volume to overcome.

If the crucial support tier holds steady through the September 11 inflation release, a retest of the upper resistance band represents the most likely scenario. A decisive break above US$81,000 could easily signal fresh momentum toward the US$82,400 swing high. Unexpected inflation data could easily break current support structures. This negative surprise would likely trigger a rapid drop toward US$78,000. The broader sector rally could extend toward US$83,000 if the primary digital asset holds above US$79,000. Alternative projects will likely continue to outperform during this extension.

A break below the crucial US$76,200 support level may trigger a broader pullback toward the US$72,000-US$74,000 range. This downside scenario becomes highly probable if the Federal Reserve signals a strict stance during its September 15 and 16 meetings. The upcoming August inflation data and the subsequent central bank gathering are critical catalysts that will strongly influence the dollar and overall risk appetite. The current trend remains cautiously bullish, but the sector remains highly vulnerable to strict surprises. Participants constantly question whether virtual commodities will decouple from traditional equities if the upcoming inflation report reignites aggressive rate-hike fears.

My assessment suggests current speculative momentum relies entirely on economic stability and continuous institutional inflows. Large capital allocators demand clear macroeconomic signals before committing fresh capital to this highly volatile asset class. The trajectory depends on whether the largest digital asset can maintain structural integrity above key thresholds as it navigates a highly uncertain global landscape.

Editor’s note: e27 aims to foster thought leadership by publishing views from the community. You can also share your perspective by submitting an article, video, podcast, or infographic.

The views expressed in this article are those of the author and do not necessarily reflect the official policy or position of e27.

Join us on WhatsAppInstagramFacebookX, and LinkedIn to stay connected.

The post From US$79,300 to US$82,400: Mapping the narrow corridor that decides Bitcoin’s September appeared first on e27.
Posted on Leave a comment

SCB 10X Identifies Six Key Takeaways for Organizations Navigating the AI Transformation, Drawing Insights from AI-VOLUTION The Series 2026

SC

Bangkok, September 2, 2026 – SCB 10X, the disruptive technology investment arm of SCBX Group, continues its AI knowledge-sharing initiative through “AI-VOLUTION The Series 2026”, a year-long online content series featuring in-depth conversations with global technology experts, founders, investors, and enterprise leaders on how organizations can adapt as AI reshapes products, business models, and ways of working.

Building on the success of the AI-VOLUTION Virtual Summit 2025, which attracted more than 5,000 participants from 88 countries and generated over 700,000 cumulative views, the 2026 series has evolved into a monthly format designed to provide ongoing perspectives on emerging AI trends and their real-world implications for businesses. The first six episodes of the 2026 series have already surpassed 100,000 views, highlighting strong audience interest in real-world perspectives on how AI is transforming organizations and industries.

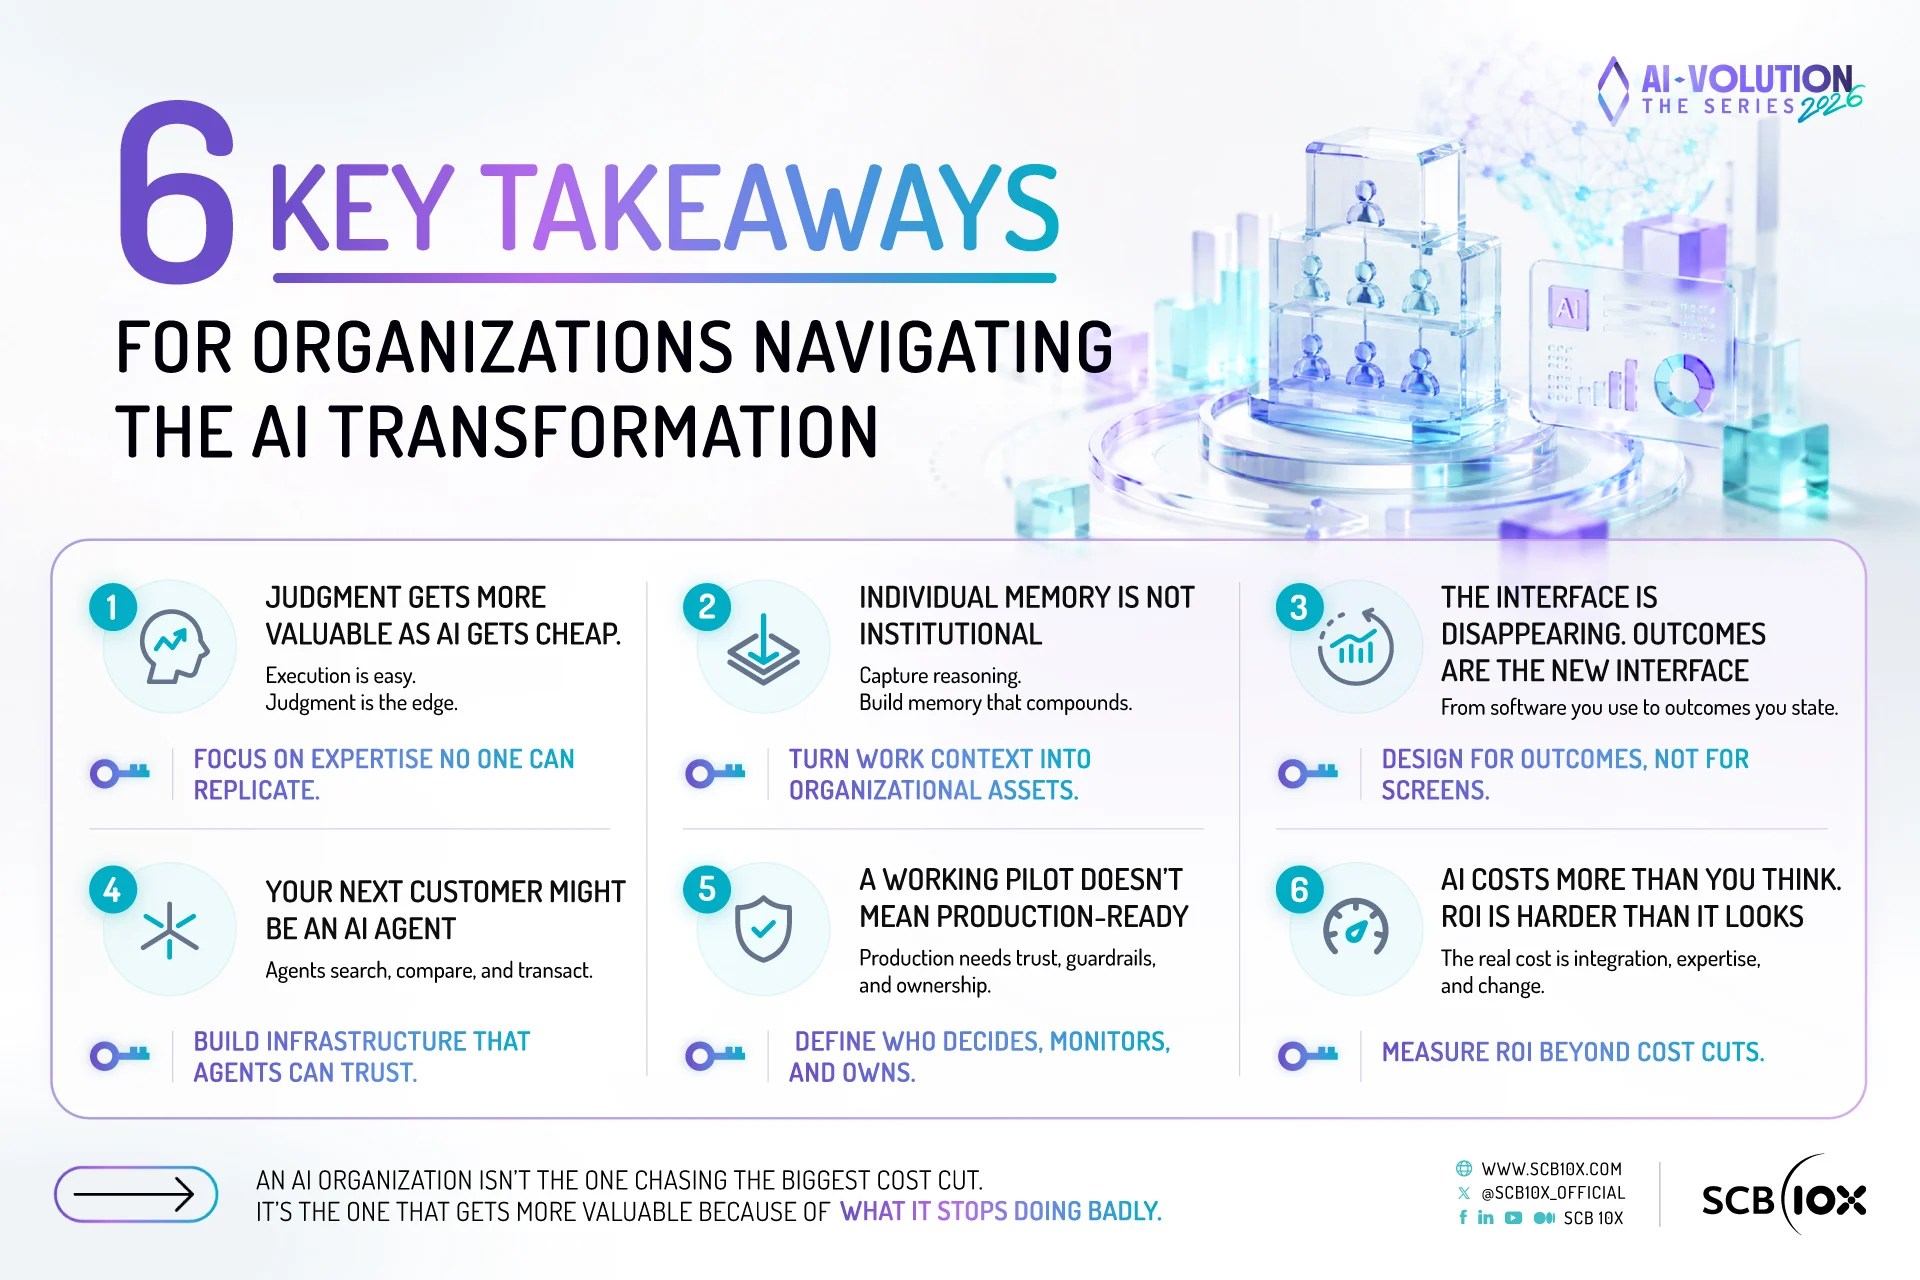
Across the series, experts and leaders from across industries have explored a central question: as AI makes it increasingly easier and faster to build products, automate work, and scale businesses, what will differentiate organizations and strengthen their competitive advantage in the AI era? Drawing from these conversations, SCB 10X’s Tech Intelligence team has distilled six key takeaways.

Six Key Takeaways from AI-VOLUTION The Series 2026

  1. As AI makes production cheaper, judgment becomes more valuable.

AI coding tools have made it increasingly easy to replicate basic software, shifting the source of competitive advantage from generic execution toward specialized expertise, differentiated products, and infrastructure that other AI systems rely on. The same dynamic extends beyond software: as AI makes it easier to produce reports, designs, and content, quality increasingly depends on human judgment, taste, and the ability to distinguish what is credible and valuable from what is simply easy to produce.

  1. Individual AI adoption does not add up to institutional memory.

While AI tools are becoming increasingly capable of remembering an individual’s context, that knowledge can leave the organization when the employee does. The series explored how enterprise AI systems, including those developed by companies such as Ema, can capture not only the outcomes of work but also the reasoning behind decisions as actions are taken. This creates the potential for organizations to build institutional memory that continuously surfaces patterns and insights that might otherwise remain invisible.

  1. The interface is moving from screens to stated outcomes.

The way people interact with software is evolving, from navigating dashboards, to conversing with AI agents, to simply stating an intended outcome and allowing the system to determine how to achieve it. SCB 10X’s venture team has been tracking emerging companies developing new user experiences and pricing models that move beyond traditional software seats, signaling a broader shift toward software that is increasingly valued and sold based on the outcomes it delivers.

  1. The next customer may not be human.

AI-driven online orders have grown dramatically, raising a new challenge for businesses: their next customer may be an AI agent browsing, comparing, and making decisions on behalf of a human. Yet many existing digital experiences were never designed for machine interaction, leading agents to find unexpected workarounds when conventional “front doors” do not work for them. The discussions highlighted the importance of deliberately building infrastructure and experiences that are ready for an agent-driven customer journey.

  1. A successful pilot does not mean AI is ready for production.

Real-world AI deployment requires far more than demonstrating that a model can complete a narrow task. Once deployed at scale, organizations must determine how systems behave under different levels of traffic, noise, uncertainty, and escalation—and who has authority when things go wrong. The series highlighted that production readiness depends on operational ownership: clear accountability for decisions, continuous monitoring, and defined processes for intervention and escalation.

  1. Companies may underestimate AI’s costs while overestimating its savings.

Discussions highlighted the gap between the apparent economics of AI and the realities of enterprise deployment. An MIT Project NANDA study found that 95% of enterprise generative AI pilots delivered no measurable result, with integration emerging as a major challenge beyond the cost of AI licenses. At the same time, reporting discussed in the series suggested that roughly one-third of roles cut for AI-related reasons over the past year were subsequently rehired, underscoring the risk of removing expertise faster than organizations can replace it. The discussions emphasized that meaningful AI ROI must account not only for deployment costs and measurable value created, but also for whether critical expertise and judgment remain within the organization.

Together, these insights point to a broader shift in how organizations should approach AI. The question is increasingly moving beyond whether AI can perform a task to how organizations can redesign the way they work, make decisions, preserve expertise, and create value around AI.

“AI-VOLUTION The Series 2026” will continue throughout the year, bringing together perspectives from the global AI ecosystem to help business leaders, entrepreneurs, and technology professionals navigate this rapidly changing landscape.

Watch the full VDO of AI After the Chatbot: 6 New Rules for Building AI Organizations: https://www.youtube.com/watch?v=pL8oJCSzgGE 

Watch all the episodes of AI-VOLUTION The Series 2026 via SCB 10X Youtube playlist: https://www.youtube.com/watch?v=p5kX1d8jSos&list=PLJCrobWNqQvvX8bfOFg8HQby9bObgwvuU

For additional content, insights, and future updates, visit SCB 10X social media channel: https://linktr.ee/scb10X

About SCB 10X

SCB 10X is the disruptive technology investment arm of SCBX Group. With an investment track record since 2016, SCB 10X has deployed over USD 500 million globally into startups in AI, blockchain, and fintech. SCB 10X has backed exceptional companies such as Together AI, Pagaya, Ripple, Fireblocks, Anchorage Digital

Beyond capital, SCB 10X partners with our portfolio founders to test, grow and scale their solutions through SCBX’s network, unlocking commercial opportunities into Thailand and Southeast Asia. Mandated as the group’s speedboat, we discover and ship state-of-the-art technologies and solutions into SCBX group. 

For more information, please visit https://scb10x.com/ 

____________________

Want updates like this delivered directly? Join our WhatsApp channel and stay in the loop.

This article was Sponsored by SCB 10x

We can share your story at e27 too! Engage the Southeast Asian tech ecosystem by bringing your story to the world.
 You can reach out to us here to get started.

The post SCB 10X Identifies Six Key Takeaways for Organizations Navigating the AI Transformation, Drawing Insights from AI-VOLUTION The Series 2026 appeared first on e27.

Posted on Leave a comment

Why Kyoto, not Tokyo, is Japan’s real deeptech bet

Ask most investors where Japan’s startup action is, and they will say Tokyo without hesitation. But at this year’s IVS 2026, one of Japan’s largest startup gatherings, a quieter story was playing out an hour’s train ride south-west: Kyoto, a city better known for temples than transistors, has quietly built one of Asia’s more interesting deeptech ecosystems.

The numbers, at least on paper, are not huge. According to Kyoto City, the ecosystem now counts more than 650 startups, over 250 of them university spin-offs, backed by more than 20 venture capital and corporate venture capital firms. Compared to Tokyo’s startup density, that is a modest showing. But scale was never really the pitch. The pitch is patience and whether patience, finally connected to global capital, can be a competitive advantage rather than a liability.

A different game from Tokyo

Tokyo and Kyoto are not competing head-on, and the split is fairly clean. Tokyo dominates in SaaS, fintech, consumer marketplaces and fast-moving AI applications, the categories where speed and scale decide winners.

Also Read: Why Japan’s booming AI market is harder to crack than it looks

Kyoto’s strength, on the other hand, sits in semiconductors, robotics, materials science, life sciences and climate and energy technology: fields where breakthroughs take years, sometimes decades, and where a rushed timeline is often a red flag rather than a virtue.

That distinction matters because Kyoto is not trying to out-run Tokyo. Its compact geography, with most of its universities, research institutes, corporations and manufacturers sitting within walking or cycling distance of each other, makes the kind of slow-burn collaboration deeptech requires easier to sustain. Ideas can move from lab bench to funding to manufacturing without leaving the region, something few cities can claim at this scale.

The case, according to the money

Don Stalter, Managing Partner at Sunshine Lake, has watched Japan since 2011, when he worked on Groupon and Airbnb’s international expansion before becoming an early backer of Deel and Canva. His read on Kyoto is unambiguous: the city has “something money can’t buy and speed can’t replicate”, a manufacturing lineage running through Nintendo, Kyocera, Murata, Omron, Shimadzu and Horiba — companies that he says chose depth over fashion and stayed independent long enough to become irreplaceable links in global supply chains.

He points to three concrete strengths. Kyoto University’s research density, which has produced a notable share of Japan’s Nobel laureates, including the iPS cell breakthroughs behind regenerative medicine. A steady renewal of talent, with roughly one in ten Kyoto residents a student. And a cultural tolerance for long timelines that, in his view, cannot simply be bought with venture capital.

But Stalter is careful not to romanticise the gap. What Kyoto lacks, he argues, is not science or talent but bridges: early-stage global capital, global customers from day one, and networks willing to treat a Kyoto founder the same way they would treat one in San Francisco. He also flags the recycling problem common to younger ecosystems, a handful of big exits whose founders and early employees reinvest back into the next generation is still largely missing in Kyoto’s case.

The founder’s view

Hide Morita, CEO of fan-engagement platform Queri and grandson of Sony co-founder Akio Morita, offers a more grounded, on-the-ground version of the same argument. Tokyo, he says plainly, has easier access to capital, customers and large corporations. What Kansai offers instead is depth — engineering and manufacturing knowledge concentrated in one place, built by companies such as Kyocera, Murata and Nintendo that became world-class by narrowing rather than diversifying.

Morita’s own company is a useful proof point of the region’s slower logic. Queri connects Japanese and Asian entertainment companies with fans overseas, where roughly 40 per cent of its users are already based outside Japan. Building the infrastructure to serve that demand, he says, is “slow, unglamorous work”, not unlike the deeptech ventures Kyoto is known for, which depend on universities, engineers, manufacturers and investors staying aligned over years rather than product cycles.

Also Read: Japan is moving into Southeast Asia faster than the West, and most brands haven’t noticed yet

Like Stalter, Morita is sceptical that capital alone solves the harder problem. Kyoto’s more than 650 startups are not short of technology, he argues; they are short of the operating experience (sales, hiring, international expansion) needed to take a lab breakthrough global. His prescription is specific: don’t try to turn Kyoto into another Tokyo or Silicon Valley. Keep the long-term mindset and technical depth, and pair it with far better access to the rest of the world.

What’s actually being built

The specifics back up the pitch. TreGem Biopharma, a Kyoto University spin-off, is developing what it describes as the world’s first tooth-regrowth drug, an antibody therapy targeting a protein called USAG-1, with an initial focus on patients born without a full set of teeth. DeepForest Technologies uses AI to analyse drone footage and identify individual tree species and carbon absorption at single-tree resolution — a granularity increasingly demanded by carbon credit buyers and by Japan’s ageing, postwar-planted forests.

Kyoto Fusioneering has taken a “picks and shovels” approach to fusion energy, building the exhaust and fuel-cycle systems fusion plants will need rather than reactors themselves, and has reportedly become a supplier to several private fusion developers internationally. EneCoat Technologies, meanwhile, is developing perovskite solar cells that generate electricity even under cloudy skies or indoor lighting, thin and flexible enough to apply to windows rather than rooftops.

None of these are Tokyo-style growth stories. They are long-horizon bets that only make sense if the surrounding ecosystem — universities, manufacturers, patient capital — stays intact long enough to see them through.

The bet, stated plainly

Kyoto’s proposition to international founders and investors is narrow but specific: a compact city where research institutions, manufacturers, government and capital sit close enough together to move fast on slow science, a manufacturing culture with genuine present-day depth in precision engineering, and a globally recognisable brand that needs no introduction.

Also Read: Beyond market entry: Japan and Southeast Asia in a fracturing world

Whether that is enough remains an open question. Deeptech ecosystems live or die on decades, not news cycles, and Kyoto’s recycling of capital and talent is still early. But the underlying argument — that a thousand years of patience, finally wired into global capital, might outlast speed — is at least a coherent one. Tokyo built Japan’s startup scene on speed. Kyoto is testing whether the opposite instinct can work just as well.

This article was originally published by Blockbox, a media outlet that reports on the Japanese startup scene.

The post Why Kyoto, not Tokyo, is Japan’s real deeptech bet appeared first on e27.

Posted on Leave a comment

The US$103K visa fee is a gift to SEA’s talent pool if the region actually wants it

Every few years, Washington slams a door and Asia is told to catch the people falling out of it. It happened after the dot-com bubble. It happened after the 2020 H-1B tightening. It is happening again now, and the instinct across Southeast Asian boardrooms and government press releases will be the same: cue the victory lap.

Before anyone in Singapore, Jakarta or Ho Chi Minh City breaks out the “brain gain” slide deck, it is worth asking whether this region has ever actually won this fight, or just told itself it did.

A door slams, again

In late August, the Trump administration proposed a US$103,265 annual fee for new H-1B visas, a near-500-fold jump from the previous US$215 charge. It follows an earlier US$100,000 fee announced last September that briefly triggered chaos — with Amazon, Microsoft and JPMorgan telling H-1B staff to rush back into the US before a midnight deadline — before a US court struck it down.

Also Read: Taiwan’s startup talent problem is a matching problem, not a shortage

The back-and-forth has not calmed anyone’s nerves. Fiscal year 2027 H-1B registrations have fallen 38.5 per cent, and workers are increasingly weighing Canada, the UK and the Gulf as landing spots instead of gambling on Washington’s next move.

On workplace forum Blind, sentiment has gone from outrage to something closer to resignation, a shift TeamBlind chief executive Sunguk Moon has called a trust signal more telling than any hiring statistic.

Indian voices reacted fastest and loudest, given that Indian nationals hold roughly 70 per cent of H-1B visas. Former NITI Aayog chief executive Amitabh Kant framed it bluntly on social media as America’s loss and India’s gain, predicting the fee would push “the next wave of labs, patents, innovation and startups” toward Bangalore, Hyderabad, Pune and Gurugram. Andhra Pradesh’s IT minister has talked up the state’s role in a national “brain gain” story built on Global Capability Centres (GCCs), the in-house offshore units multinationals now use for product development and R&D rather than back-office support. India already hosts around 1,700 of them, generating an estimated US$68 billion in direct value-add, and more than 35,000 returning technologists have joined GCCs, homegrown startups or global delivery centres since 2022.

We have run this experiment before

This is not a new story, which is precisely the point. Research from economists Gaurav Khanna and Nicolas Morales on the original dot-com-era H-1B cap found that Indian engineers who were shut out of the US, or who returned home after their visas expired, helped build India’s software export industry into a global force — a genuine, measurable case of one country’s restriction becoming another’s foundation. It is the closest thing this debate has to a control group, and the finding cuts both ways: brain gain is real, but it took a generation to compound, not a single visa cycle.

Southeast Asia’s own attempt to capture skilled migration has moved at a similarly unglamorous pace. Singapore’s Overseas Networks & Expertise Pass (ONE Pass), the country’s marquee tool for luring senior global talent with no requirement to work for a single employer, has grown from roughly 3,600 holders at the end of 2023 to 8,500 by the end of 2025. Respectable growth,  except official figures show only around one in six ONE Passes issued in 2024 went to genuinely new entrants rather than people already working in Singapore switching pass types.

Also Read: SEA’s AI talent and infrastructure: Building the foundation for regional tech leadership

Compare that with Hong Kong’s rival Top Talent Pass Scheme, which had drawn more than 150,000 applications and approved over 120,000 within three years by early 2026. Singapore is not losing this race by default; it simply is not winning it by nearly the margin the press releases imply.

What would actually make this a gift

Singapore is not standing still. From January 2027, its ONE Pass will gain a dedicated AI and Tech track, alongside rising salary floors for Employment Pass and S Pass holders, a deliberate bet on quality over volume. But a work pass, however well designed, addresses only the entry point. It says nothing about what happens once someone lands: whether the ecosystem around them can actually absorb senior engineering leadership, whether compensation and equity structures compete with what a US offer once did, and whether a returning or relocating technologist finds a real career ceiling or a glass one.

That is where the H-1B shock differs from a straightforward regional windfall. The people most likely to leave the US over a six-figure visa fee are not junior developers; they are precisely the senior, experienced hires that Southeast Asian startups have always struggled hardest to attract and retain, because the region’s funding rounds, valuations and equity culture still lag Silicon Valley’s. A US$103,265 fee does not automatically convert into a queue of veteran engineers knocking on Grab’s or Sea’s door. It converts into a queue of people evaluating every plausible alternative to the US at once, with Toronto, London, Dubai and Bangalore competing for the same talent Jakarta or Manila would also like to claim.

The real test

If Southeast Asia wants this to be more than a talking point, the fix is unglamorous: close the pay gap for senior technical and research roles, make equity genuinely competitive rather than symbolic, and treat immigration policy as one lever among several rather than the whole strategy.

India’s GCC boom did not happen because Bangalore issued a nicer visa; it happened because the work itself moved there, product mandates and all. Singapore’s ONE Pass numbers will keep climbing regardless of what Washington does next, because the pass was never really about H-1B refugees in the first place.

Also Read: The outlier advantage: Why your startup needs glitch talent

The US$103,265 fee is real, and it will genuinely push some skilled workers out of America’s orbit. Whether Southeast Asia captures them, or simply watches them pass through on the way to somewhere with deeper pockets, depends on decisions the region’s founders, investors and policymakers were already supposed to be making before this latest headline gave them an excuse to feel optimistic instead.

The post The US$103K visa fee is a gift to SEA’s talent pool if the region actually wants it appeared first on e27.

Posted on Leave a comment

GCash operator Mynt wins SEC approval for up to US$1.63B Philippine IPO

The long-anticipated public market debut of GCash operator Mynt has moved a step closer, after the Philippine Securities and Exchange Commission approved the company’s initial public offering worth up to about US$1.63 billion.

In a statement on Friday, the SEC said its Commission En Banc had resolved to render effective Mynt’s registration statement covering up to 66.9 billion common shares, subject to the company meeting remaining regulatory requirements.

Also Read: 48 PE investors, US$3.96B deployed, and not a single IPO exit in five years. Something is broken.

The decision clears a key hurdle for what could become one of the Philippines’s largest listings in recent years, and a closely watched test of investor appetite for Southeast Asian fintech at a time when public markets remain selective about growth-stage technology companies.

Mynt, the company behind mobile wallet and financial services platform GCash, plans to offer up to 1.61 billion common shares through a primary offer. A selling shareholder will also sell up to 6.42 billion shares, while the transaction includes an overallotment option of up to 1.20 billion shares.

The shares will be priced at up to around US$0.18 each. Assuming the overallotment option is fully exercised, Mynt expects to raise net proceeds of up to about US$1.58 billion from the total offer. Of that, roughly US$264 million in net proceeds from the primary offer will be used to fund growth in digital financial services, product development, and general corporate purposes.

Based on the latest timetable submitted to the SEC, the offer period will run from October 6 to 12. Mynt is aiming to list on the Main Board of the Philippine Stock Exchange on October 20 under the ticker symbol “GCASH”.

A market bellwether for Southeast Asian fintech

For the Philippine market, the approval is significant not only because of the size of the deal, but because of what Mynt represents. GCash has become one of the country’s most recognisable consumer technology brands, riding the rapid shift from cash to mobile payments during and after the pandemic. Its app has expanded well beyond peer-to-peer transfers and bills payment into savings, credit, insurance, investments, and merchant services.

That evolution mirrors a broader Southeast Asian fintech playbook. Across the region, digital wallets started as payments tools, often subsidised heavily to win users and merchants. Over time, the strongest platforms have tried to move into higher-margin financial services, using transaction data and distribution scale to offer lending, wealth products, and insurance.

The Philippines has been one of the more fertile markets for this model. The country has a young, mobile-first population, a large base of underbanked consumers, and a fragmented geography that makes branch-heavy banking expensive. Remittances, both domestic and overseas, are also central to household finances, creating demand for low-cost digital money movement.

Also Read: When IPOs freeze, liquidity finds another way

But scale does not automatically translate into public market success. Investors will look beyond GCash’s brand recognition and user base to assess the durability of its revenue, the economics of its lending and financial services products, and the cost of maintaining growth in a competitive market. The listing will likely be read as a valuation benchmark not just for Philippine tech, but for regional fintechs that have spent years waiting for clearer IPO windows.

Lower float rule gives large issuers more room

Mynt is also the first company to benefit from the SEC’s lower public float requirement for large issuers. The regulator allowed the company to have a minimum initial public float of 12 per cent, instead of the usual 15 per cent.

A public float refers to the portion of a company’s shares that is available for public trading. Lowering the requirement for large issuers can make it easier for sizeable companies to list without forcing existing shareholders to sell a larger stake at the IPO stage. For regulators and exchanges, the trade-off is between attracting marquee listings and ensuring enough liquidity for public investors.

The Philippines, like several markets in Southeast Asia, has been trying to deepen its capital markets and persuade more high-growth domestic companies to list at home rather than look offshore. A successful GCash listing would give the Philippine Stock Exchange a rare technology anchor at a time when regional exchanges are competing to host the next generation of consumer internet, fintech, logistics, and climate-tech companies.

Singapore has long positioned itself as the region’s financial hub, while Indonesia has seen major listings from digital economy names such as Bukalapak and GoTo. The Philippines has produced fewer large public tech listings, making Mynt’s IPO especially important for local market sentiment.

What Mynt plans to do with the money

The company has said that proceeds from the primary offer will go towards digital financial services growth, product development, and general corporate purposes. That broad use of funds suggests Mynt is still investing for expansion rather than treating the IPO purely as a liquidity event.

In practical terms, product development could mean deeper work across areas such as credit scoring, fraud prevention, wealth management tools, merchant services, and embedded finance. In emerging markets, digital finance platforms often face a delicate balance: they need to widen access to financial products, but must also manage credit risk, cybersecurity, compliance, and consumer protection.

That scrutiny is likely to intensify once Mynt becomes a listed company. Public investors will expect more transparency around revenue mix, margins, bad loans if lending becomes a bigger contributor, and the regulatory risks attached to financial services. The company will also need to show that it can keep users engaged even as rivals push their own wallets, banks, and payment ecosystems.

The competitive field

GCash’s most direct domestic challenger is Maya, the fintech platform under Voyager Innovations and backed by PLDT, which has built its own wallet, payments, and digital banking ecosystem. Traditional banks in the Philippines are also accelerating their digital offerings, while card networks and payment processors remain deeply embedded in merchant transactions.

Regionally, Mynt sits in a crowded field of wallet and super-app players. Grab has built payments and financial services across several Southeast Asian markets, while Sea Group’s ShopeePay and SeaBank link commerce, payments, and banking. In Indonesia, GoTo’s GoPay and DANA compete aggressively for wallet share, while Vietnam’s MoMo remains one of the region’s best-known standalone e-wallets. Malaysia’s Touch ’n Go eWallet has also scaled through transport, retail, and financial services use cases.

The question for Mynt is whether GCash can maintain its domestic dominance while proving that its model has the margins and discipline public investors demand. Unlike regional super-apps that operate across multiple countries, Mynt’s strength is concentrated in the Philippines. That focus can be an advantage if it produces deeper local penetration, but it also limits the geographic diversification that some investors may prefer.

A listing that could set the tone

Mynt’s IPO comes at a time when Southeast Asian technology companies are being judged more soberly than during the low-interest-rate boom. Growth still matters, but profitability, governance, and capital efficiency now carry more weight. The region’s private markets have adjusted to this reality; a major public listing will show how far that reset has travelled.

Also Read: The IPO window is open, and SEA startups are walking through

For Philippine startups, the debut could be a morale boost. A strong listing would show that domestic capital markets can support large technology companies and provide an exit path for founders, employees, and early investors. A weak reception, however, would reinforce caution around tech valuations and push more late-stage companies to delay IPO plans.

Either way, GCash’s move to the public market will be watched far beyond Manila. It is not just a fintech IPO. It is a test of whether one of Southeast Asia’s most widely used digital finance platforms can translate everyday consumer behaviour into a durable public company story.

The post GCash operator Mynt wins SEC approval for up to US$1.63B Philippine IPO appeared first on e27.

Posted on Leave a comment

Laters.com raises US$1.5M to expand flexible flight payments

[L-R] Laters.com co-founders Arvin Singh and Alex Yardley

For most travellers, the anxiety of booking a flight starts before the airport. A fare appears, the dates work, and then comes the harder question: can it be paid for today?

Laters.com, the Singapore-founded online travel agency previously known as Fly Fairly, is trying to build a business around that moment. The company has raised US$1.5 million in seed funding led by XBO Ventures, the investment arm of digital-asset platform XBO.com, while completing its rebrand from flyfairly.com to laters.com.

This round comes over a year after the firm acquired LFG, a social travel discovery engine known for its viral, Gen Z-focused user experience.

Also Read: What travel tech can look like for the travel industry’s revival

The startup sells flights across more than 650 airlines and lets customers pay through over 100 methods, including digital wallets, cryptocurrencies, and around 40 buy-now-pay-later and instalment options. Its pitch is not that it has cheaper fares than everyone else, but that it gives travellers more ways to complete a booking once they find one.

That distinction matters in Southeast Asia, where online travel demand has returned strongly after the pandemic, but payment behaviour remains fragmented. Credit card penetration varies widely across the region, while wallets, bank transfers, instalment products and local payment rails often dominate daily spending. For travel platforms, that creates a gap: demand may exist, but checkout can still fail if customers cannot use their preferred payment method.

Laters.com says the majority of its payment volume is already non-card, which it describes as the inverse of much of the wider travel industry.

“Nobody should lose the fare they found because payday is two weeks away,” said Alex Yardley, founder and CEO of Laters.com. “Family, work, a wedding: some trips cannot wait. Laters.com fixes the price today and spreads the cost, so the people who plan ahead are not the ones who pay the most.”

From Fly Fairly to Laters.com

Laters.com launched from Singapore in August 2024 and says it has been profitable every month since February 2025. The company claims it is now on a run rate of more than one million travellers a year searching for flights on its platform. The United States has become its largest market, despite the company being headquartered in Singapore.

That geographic mix hints at the nature of the product. Buy now pay later, or BNPL, is well established in markets such as the US, Australia and parts of Europe, but Southeast Asia has also become an important testing ground for alternative payments. Players such as Atome, Kredivo, Grab, Shopee and others have trained consumers to split purchases into instalments, even as regulators keep a closer eye on consumer debt and transparency.

Flights are a particularly sharp use case because prices can move quickly and the ticket size is often much higher than a typical e-commerce purchase. Laters.com says customers using local and flexible payment methods book 35 per cent more often and spend 24 per cent more per booking than card users, citing a Stripe case study. It also says BNPL customers generate an average order value more than three times higher than card users.

Those figures explain why travel companies are paying closer attention to checkout design. In a market where customer acquisition costs are high and margins can be thin, a failed payment is not a minor technical issue. It can be the difference between a booked trip and a lost customer.

Crypto at checkout, not as a gimmick

The other part of Laters.com’s proposition is cryptocurrency. The platform accepts stablecoins and more than 70 other cryptocurrencies, settled at checkout like any other payment method. According to the company, crypto customers spend more than twice as much as the average customer, typically on long-haul trips and higher cabin classes.

Also Read: The unsexy side of SEA traveltech: eSIMs, visas and hourly hotels win big

That does not mean crypto has become a mainstream way to buy airline tickets. In much of Southeast Asia, digital assets remain volatile, unevenly regulated and often associated more with trading than day-to-day payments. But stablecoins, which are designed to track the value of fiat currencies such as the US dollar, are increasingly being watched by fintech firms as a possible bridge between crypto users and practical spending.

For XBO Ventures, that appears to be the investment thesis.

“We back companies that turn digital assets into something people actually spend. Laters.com has done that at one of the sharpest points of friction there is: paying for a flight,” said Dor Maman, co-founder and CFO of XBO. “The majority of its volume already moves outside the card networks, and that is where we think this market is going.”

XBO Ventures has also backed payments infrastructure company Rapyd, participating in its US$500 million Series F round, according to the company’s notes to editors.

A crowded field, but a narrower wedge

Laters.com sits at the intersection of several competitive categories. In online travel, it faces large platforms such as Booking Holdings, Expedia Group, Agoda, Traveloka, Trip.com and AirAsia MOVE, many of which already offer flights and have deep supplier relationships. In flexible travel payments, companies such as Alternative Airlines have long promoted instalment options for flights, while Travala is known for allowing crypto payments across travel bookings.

In Southeast Asia, superapps and local travel platforms also have the advantage of distribution, loyalty programmes and embedded wallets.

Laters.com’s narrower wedge is payment breadth: instead of competing mainly on inventory or price, it is trying to become the travel checkout that adapts to how younger consumers already pay elsewhere.

Yardley’s background also reflects that mix of travel and commerce. Before founding Laters.com, he spent two decades across travel and e-commerce, including roles on eBay’s EMEA leadership team, as Senior Director at Booking Holdings leading partnerships for Agoda and Booking.com across Asia Pacific, and most recently as Managing Director at ShopBack.

The company is also publishing two free tools aimed at travellers navigating the fragmented pay-later market. One is a country-by-country guide to fly now pay later providers, covering options such as Klarna, Afterpay, Zip and Atome. The other is the Laters.com Payment Score, which rates pay-later providers available at checkout out of 10 based on repayment flexibility, interest rate, eligibility and approval process.

Laters.com says no provider pays to be scored, ranked or placed, and that it earns the same margin regardless of how a traveller pays. That claim will matter if the platform wants to be seen as a neutral guide rather than another checkout funnel.

The new funding will go towards brand growth, expansion of the core flight business, and new products and verticals. Yardley hinted that the company’s ambitions may stretch beyond travel.

Also Read: Travel is back, and it’s more cutthroat than ever

“Millennial and Gen Z travellers have spent a decade adapting to a booking experience built for their parents,” he said. “We built Laters.com around how this generation actually pays, and it turns out what we built works well beyond flights.”

For now, Laters.com is making a focused bet: that the next wave of online travel growth will not only come from more destinations or cheaper fares, but from giving travellers more control over how and when they pay.

The post Laters.com raises US$1.5M to expand flexible flight payments appeared first on e27.

Posted on Leave a comment

The AI wrapper reckoning has reached SEA’s funding tables

Southeast Asia’s Native AI companies raised US$4.1 billion in the first seven months of 2026, more than double 2025’s full-year total, according to Tracxn’s Southeast Asia AI Startup Landscape report.

On a headline chart, that looks like a region riding the same AI wave as everyone else. Strip out a single transaction and the picture changes completely: Kling AI’s US$2.8 billion Series D alone accounted for roughly 68 per cent of that total. Take it out, and Southeast Asia’s AI companies raised closer to US$1.3 billion, and the number of disclosed rounds fell from 41 in 2025 to just 23 this year.

Also Read: AI is eating the world and startups are riding the infrastructure wave

Bigger cheques, fewer of them, concentrated in fewer companies. That is not a funding boom. It is a filtering mechanism, and most of the region’s AI “wrapper” startups (the ones offering a thin, prompt-engineered interface over someone else’s foundation model) are on the wrong side of the filter.

The wrapper reckoning is already global

“Last year demonstrated that it’s difficult to survive as an AI wrapper company,” George Mathew, MD at Insight Partners, told Crunchbase News in a trend piece published in January.

That sentiment has hardened into investor consensus through 2026. PitchBook analysts have documented investors nearly halting funding for horizontal, undifferentiated AI platforms, favouring companies with a proprietary data advantage, genuine compute economics, or workflow lock-in that a general-purpose chatbot cannot replicate overnight. The pitch-deck advice circulating among Silicon Valley accelerators this year is blunt: if a reviewer’s first reaction is “OpenAI wrapper,” the meeting is already over.

The mechanism is straightforward. Every capability a wrapper startup builds on top of GPT, Claude, or Gemini can, in principle, be absorbed into the next release of that same model. A startup whose entire product is a nicer interface to somebody else’s intelligence has no moat, only a head start, and head starts in this market now measure in months.

Southeast Asia’s version of the squeeze

The regional data bears this out with uncomfortable precision. Singapore alone accounts for roughly US$9.3 billion of Southeast Asia’s cumulative Native AI funding since 2019. On the other hand, Vietnam, Malaysia, Indonesia and Thailand have collectively raised less than US$40 million combined.

AI infrastructure (foundation models, compute platforms, and the picks-and-shovels layer) was the single most heavily funded segment in 2026, pulling in US$4.3 billion across 56 rounds, led by Kling AI and MiniMax’s US$1.2 billion round.

Also Read: Fintech, DeFi and applied AI define Southeast Asia’s new venture discipline

Investors are not walking away from Southeast Asian AI. They are walking straight past the application layer to write concentrated cheques into infrastructure and foundation-model plays domiciled almost entirely in one city-state.

That leaves a large, under-discussed population of genuinely useful but thinly differentiated GenAI tools — customer-service chat layers, document summarisers, marketing-copy generators built for SEA-specific languages and workflows — competing for a shrinking pool of smaller, earlier-stage cheques. Some of that work is legitimately valuable to the SMEs and enterprises using it. Very little of it, on current investor logic, is fundable as a stand-alone venture-backed company.

What actually separates a wrapper from a company

The startups clearing the bar globally share a pattern worth naming plainly, because it is achievable, not mystical. They own an exclusive dataset a general model cannot replicate, which is proprietary transaction, behavioural or domain data accumulated through actual usage. They have workflow lock-in deep enough that switching costs, not model quality, keep customers paying. And they can show a credible path to serving users profitably at scale, rather than assuming compute costs will simply keep falling in their favour.

For Southeast Asia specifically, that argues for leaning harder into precisely the terrain that is hardest for a Silicon Valley foundation model to serve well from the outside: hyper-local language data across Bahasa, Vietnamese, Thai and the region’s dozens of dialects; regulatory and compliance workflows tied to specific national frameworks; and vertical depth in sectors (logistics, agritech, healthcare compliance), where the value sits in proprietary operational data, not in the fluency of the underlying model.

The quiet exit ramp: consolidation, not collapse

It would be too simple to say wrapper startups simply fail. The more common outcome globally has been quiet absorption: talent acquihires, small tuck-in acquisitions by larger platforms wanting a distribution channel or a regional team, or founders folding a standalone product into a feature inside someone else’s suite.

Crunchbase News has tracked over 127,000 tech job cuts at US-based companies in 2025 alone, a chunk of it AI-adjacent restructuring rather than pure failure — talent being reallocated rather than simply let go.

Southeast Asia should expect the same pattern rather than a wave of dramatic shutdowns: wrapper startups that raised a seed round in 2024’s enthusiasm quietly becoming a feature at a larger fintech, super-app, or enterprise software company rather than an independent Series A story. That is a reasonable outcome for a founding team, but it is a very different one from the venture-scale exits the 2024 funding wave implicitly promised investors and early employees.

The uncomfortable question for founders and investors alike

None of this means Southeast Asia’s AI funding story is disappointing; US$4.1 billion is real capital, and infrastructure investment of this scale builds genuine regional capability over time. But founders currently raising on a “we built a nice interface to an LLM” pitch should treat 2026’s numbers as a warning rather than encouragement. The rounds are getting bigger for companies that have already proven defensibility, and smaller, or non-existent, for everyone else.

Also Read: Where AI money is made, and where SEA founders should actually compete

Investors, for their part, might ask themselves a harder question than “does this have a moat”: whether Southeast Asia’s own concentration of AI capital into Singapore-domiciled infrastructure plays is creating exactly the kind of regional imbalance the ecosystem has spent a decade trying to correct.

A funding boom that leaves Vietnam, Indonesia, Malaysia and Thailand collectively under US$40 million is not obviously healthier than the wrapper glut it is replacing; it is simply a different kind of concentration risk, one investors are currently far less inclined to name out loud.

The post The AI wrapper reckoning has reached SEA’s funding tables appeared first on e27.

Posted on Leave a comment

The Podular future: Why AI demands a new organisational architecture

Over the past year, I have become increasingly convinced that most people are looking at AI through the wrong lens.

The dominant conversation is still about tools, productivity, automation, and replacement. But I think the deeper shift is structural. AI is not just changing how work gets done. It is changing what kind of organisational structures still make sense.

The solo future is real. I think we need to stop debating that.

One person with the right AI stack, workflows, systems, and distribution channels can now produce what entire teams struggled to deliver five years ago. A strategist can operate without an agency. A designer can launch products without engineers. A founder can manage operations, content, research, and customer support from a laptop.

The economics of execution are collapsing.

Microsoft’s 2025 Work Trend Index describes the emergence of what it calls the “Frontier Firm,” organisations increasingly structured around humans coordinating AI agents rather than scaling through traditional headcount. Chinese municipalities have also begun supporting AI-powered one-person businesses as part of economic development strategy.

The one-person company is no longer an internet fantasy. It is becoming infrastructure.

But the more I studied this shift, the more I felt something was missing from the conversation. AI scales execution. It does not scale resilience. And I think that distinction is about to matter enormously.

Right now, the internet celebrates the one-person company as the final form of entrepreneurial freedom. But I believe most people are mistaking leverage for durability.

A solo operator may now produce venture-scale output. But the business itself often remains structurally fragile. One illness. One burnout spiral. One family emergency. One cognitive collapse. Suddenly the entire system stalls because the company is still architecturally tied to a single nervous system.

The industrial company had redundancy but poor agility. The solo company has agility but poor redundancy. And I believe the next organisational architecture will emerge from resolving that tension.

Not the corporation. Not the startup team. Not the one-person empire. The pod.

I call this model Podular. And I believe it represents a deeper shift toward what I would describe as coordinated sovereignty, independent operators selectively integrating around resilience, continuity, and strategic leverage without recreating institutional bureaucracy.

The evidence does not yet prove the pod. But it proves the pressure making the pod inevitable.

What I think AI is really unbundling

The LLC was designed for an industrial world. It assumed offices, payroll, departments, managerial hierarchy, and permanent employment relationships. Growth meant adding people because coordination required physical organisational infrastructure.

AI is dismantling those assumptions.

Today, scale increasingly comes from systems rather than staffing. A properly configured operator can leverage AI agents, automation pipelines, APIs, synthetic media, and global digital distribution to achieve output previously reserved for institutions.

This is why the one-person company is becoming economically viable. The margins are extraordinary. The burn is tiny. The velocity is real.

Also Read: Fintech, DeFi and applied AI define Southeast Asia’s new venture discipline

But the one-person company still carries a structural flaw that AI does not solve: key-person fragility.

Research from the National Bureau of Economic Research shows investors consistently evaluate management risk alongside market and business risk. Stability matters. Continuity matters. Survivability matters.

AI changes the leverage equation. It does not remove the fragility equation. And I think that is where the real redesign of work begins.

What I mean by Podular

Podular is not a startup model. It is not a co-op. It is not a collective. And it is not decentralisation disguised as culture.

It is a resilience architecture.

A pod is a small network, usually three to seven sovereign operators, who coordinate without fully merging.

Each person keeps their autonomy, identity, upside, and operational independence. But they intentionally create selective interdependence around continuity, infrastructure, resilience, and strategic spillover.

The architecture matters.

The pod shares backup capacity. It cross-trains critical workflows. It maintains operational continuity if one member disappears temporarily. It develops shared assets without requiring permanent payroll structures.

Most importantly, it distributes fragility without recreating bureaucracy. That last part is critical.

I do not think the future of work is moving back toward large institutional teams. The coordination overhead is too expensive and too slow. But pure soloism is also unstable at scale.

Podular sits between those worlds. It preserves the speed of sovereignty while introducing institutional resilience.

Coordinated sovereignty

For decades, modern work oscillated between two poles: institutional dependency or individual independence.

I think the AI economy is creating pressure for a third model: coordinated sovereignty.

Independent operators who remain autonomous while selectively integrating around continuity, intelligence-sharing, resilience, and judgment.

Also Read: Who’s building AI for the way Southeast Asia actually speaks?

And I think this matters because AI is changing what organisations fundamentally optimise for.

In the industrial era, organisations optimised for labour aggregation. In the software era, they optimised for information flow. In the AI era, I believe organisations may increasingly optimise for judgment continuity under conditions of extreme leverage.

That changes how we think about teams. It changes how we think about founders. It changes how we think about scale itself.

The companies that dominate the next decade may not necessarily be the largest employers. They may simply become the most resilient cognitive networks.

The deeper shift

Most people still think AI’s primary impact is automation. I think the deeper impact is organisational decomposition.

AI is dissolving the assumptions that justified the industrial company in the first place. Payroll, hierarchy, departments, and permanent staffing increasingly look like expensive coordination systems designed for a world where intelligence and execution were scarce.

But intelligence is no longer scarce. Judgment, continuity, resilience, and strategic coherence are becoming the new constraints.

That is why I believe Podular matters. Not because the pod has already won. But because the pressures producing it are becoming impossible to ignore.

The solo future is real. But I believe the resilient future may be podular.

Not a company. Not a collective. Not a network. A resilience architecture for sovereign operators operating under extreme leverage.

Increasingly, I believe the defining challenge of the AI economy will not be intelligence itself, but how humans remain coherent, resilient, and strategically aligned in a world where intelligence is abundant and coordination is unstable.

Editor’s note: e27 aims to foster thought leadership by publishing views from the community. You can also share your perspective by submitting an article, video, podcast, or infographic.

The views expressed in this article are those of the author and do not necessarily reflect the official policy or position of e27.

Join us on WhatsAppInstagramFacebookX, and LinkedIn to stay connected.

The post The Podular future: Why AI demands a new organisational architecture appeared first on e27.

Posted on Leave a comment

AI has answers, experience has judgment

Ask AI how to improve a factory, a clinic, a logistics company, or a retail business, and it will have plenty to say.

It can list ideas, explain trends, draft plans, compare options, and make a rough proposal sound persuasive. In a few minutes, it can produce the kind of first draft that once took a junior team days.

That is useful.

It is also easy to mistake useful information for good advice.

AI can suggest 20 ways to improve a factory. The person who has spent 10 years on that factory floor may know which 19 will fail by Friday.

That is not because the experienced person knows more facts. AI may have more facts than either of you can read in a lifetime.

It is because experience gives people judgment.

Answers are becoming cheap

For a long time, access to information was an advantage. If you knew where to look, which expert to call, or how to write a decent first draft, you could move faster than someone who did not.

AI is lowering that advantage quickly.

Research summaries, product ideas, basic code, marketing copy, customer emails, and business plans are becoming faster and cheaper to create. The cost of a first attempt is approaching zero.

Also Read: The transformation ecology crisis: How AI is exposing the hidden fragility of high-performing teams

This is good news for people starting with less money or fewer connections. A graduate can explore an idea without hiring a consultant. A small business can analyse feedback without a large research team. A retrenched manager can turn years of experience into a clearer plan for a new service or product.

But when everyone can get an answer, the value shifts to deciding which answer matters.

Experience is a filter

Domain expertise is not a collection of facts stored in someone’s head. It is a filter built through repetition.

It tells a nurse which symptom matters first. It tells a procurement manager which supplier promise will collapse under pressure. It tells a mechanic which sound is serious. It tells a founder which customer complaint is a real market signal and which one is simply a loud opinion.

This kind of knowledge is often hard to explain because it is practical. It is built from bad decisions, difficult customers, failed projects, missed deadlines, and work that went wrong when the presentation said it should go right.

AI can give an expert more options. It can help them see patterns, organise information, and test ideas. But it cannot know the local constraints unless someone who understands them provides the context.

That makes experienced people more important, not less.

The best prompts come from people who know the work

A weak question gets a weak answer.

Ask AI, “How can I improve my logistics business?” and you will receive a polished set of general suggestions. Ask, “How can I reduce failed same-day deliveries in Jakarta during peak rain, without adding drivers or breaking our margin?” and the answer becomes more useful.

The difference is not the tool. It is the person asking.

Domain experts know what to include in the question. They know which limits cannot be ignored. They know the customer, the workflow, the budget, the regulation, and the inconvenient detail that changes everything.

Also Read: Why Malaysia’s AI Nation 2030 plan matters for B2B startups

That is why a person with real experience can use AI as leverage. They can turn a broad suggestion into a practical test. They can spot an idea that will not survive the real world. They can notice a useful improvement that someone outside the industry would never have seen.

Creation may be cheap, judgment is not

As the cost of producing a first draft falls, creating something average will become easier.

The valuable work will be deciding what is worth creating at all.

This matters for graduates. The goal is not only to learn how to use AI. It is to get close to real work, real customers, and real consequences. Those experiences create the judgment that makes AI useful.

It also matters for workers who are retraining after a career change. Years spent in an industry are not obsolete because a chatbot can explain the industry. Practical knowledge is often the best starting point for a service, product improvement, or invention.

And it matters for SMEs. Their most valuable knowledge may sit with the people who talk to customers, run the machines, manage the suppliers, and fix problems when nobody else knows what to do.

If that knowledge leaves with an employee, it may leave without being captured. If it is noticed, documented, and developed, it may become a better product, a trade secret, a patentable invention, or a stronger way of working.

AI helps expertise travel further

The hopeful story is not that AI replaces the expert. It is that AI can help the expert do more.

A food producer can explore ways to reduce waste. A technician can turn a recurring repair into a design improvement. A logistics manager can use operational data to test a better route or handover process. A clinician can identify a problem in a care journey and explore a safer solution.

The tool reduces the cost of exploration. The expert supplies the judgment.

That combination is powerful because it lets practical experience travel further. It can move from a private insight to a documented process, a tested product, a protected invention, or a business that serves more people.

The future will reward people who know how to use AI. But it will reward even more those who know what AI should be used for.

AI has answers.

Experience knows which ones matter.

If you have practical knowledge that could become a product, process, or invention, start brainstorming it at IPGuru.ai.

Editor’s note: e27 aims to foster thought leadership by publishing views from the community. You can also share your perspective by submitting an article, video, podcast, or infographic.

The views expressed in this article are those of the author and do not necessarily reflect the official policy or position of e27.

Join us on WhatsAppInstagramFacebookX, and LinkedIn to stay connected.

The post AI has answers, experience has judgment appeared first on e27.

Posted on Leave a comment

The real test of ethical AI is whether a frontline employee can challenge it

A great deal of ethical AI discussion still happens at a distance from the people who live with the system every day. It happens in governance forums, legal reviews, executive updates, risk committees, and product documents. All of that has value, but none of it answers the most revealing question.

When the system makes a bad call, can the person closest to the customer, patient, claimant, applicant, or case actually challenge it?

Contestability is the missing centre of ethical AI

Many organisations speak about fairness, accountability, transparency, and safety. Far fewer build properly for contestability. That matters because a system can be documented, monitored, and technically explainable, while still being very difficult to challenge in practice.

Contestability means more than having an override button buried somewhere in the workflow. It means the system is designed so that human disagreement is expected, legitimate, and operationally supported. It means people are not merely allowed to question an output in theory. They are able to do so without being punished by time pressure, managerial pressure, or the quiet cultural message that the machine is usually better.

This is the point many companies still miss. They think ethics is mainly about how the model behaves. It is also about how much room the organisation gives humans to resist the model when reality no longer fits the output.

Frontline employees often see harm before leadership does

One reason this question matters so much is that frontline employees are usually the first people to see where the system is breaking. They hear the confusion in a customer’s voice. They notice when a recommendation does not fit the case history. They see when a decision is technically consistent but practically absurd. They feel the human consequences before those consequences become a trend line in a monthly review.

Yet in many organisations, the frontline sits low in the hierarchy of trust. Their judgement is treated as anecdotal. Their objections are seen as local friction. Their escalations are sometimes tolerated, but not welcomed. The machine may be backed by data science, product, engineering, and leadership optimism, while the employee challenging it is backed only by experience and instinct.

Ethical AI becomes fragile when the people nearest to lived reality are expected to absorb the consequences of bad outputs without having the standing to challenge them. In those environments, the business still tells itself that humans remain in control. In practice, the human role has narrowed into delivery and damage management.

Also Read: AI agents could help Southeast Asian firms untangle cross-border payment costs

Override is not meaningful if it carries career risk

A lot of companies can point to formal override mechanisms. They will say the employee can escalate, pause the process, or route the case for review. On paper, that sounds reassuring. In reality, the value of override depends entirely on the surrounding culture.

Can a frontline employee challenge the model without being seen as inefficient?

Can they do it without creating a delay they will later be blamed for?

Can they do it without needing to prove the system wrong to a higher evidential standard than the system needed to make the recommendation in the first place?

Can they do it repeatedly if a pattern emerges, or only occasionally before they are labelled difficult?

Most organisations want the comfort of human judgement without the cost of supporting it

This is where the issue becomes uncomfortable in a useful way. Many firms want to claim that a human remains in the process, but they do not want to pay the operational price of making that human genuinely powerful.

Real challenge rights are expensive. They slow some decisions down. They require training. They require better case design, better escalation flows, and managers willing to back people who raise concerns. They require enough slack in the system for employees to think rather than merely process. They require leaders to accept that some machine recommendations will be questioned not because the model is broken, but because human reality is messy.

That is a much harder model than symbolic oversight.

So companies often settle for a compromise they do not describe clearly. The employee remains present, but not empowered. The organisation gets the reassurance of human involvement and the productivity profile of machine-led processing. The frontline becomes a moral buffer rather than a real decision maker.

Ethical AI depends on organisational, not just technical restraint

There is a tendency to frame ethical AI as a problem of model limits. Better testing, clearer thresholds, stronger policies, safer deployment. These all matter, but they do not solve the core institutional question.

Does the organisation have the courage to let people close to the work challenge the system, even when doing so slows things down, complicates reporting, or disrupts the story that the product is performing well?

Also Read: When AI starts thinking for us

That is the harder test because it touches power. It asks whether a call centre agent, claims reviewer, nurse, support specialist, operations analyst, or case worker can force the organisation to confront a failure before leadership is ready to admit it. It asks whether managers will protect that challenge or quietly discourage it. It asks whether product and engineering teams are willing to hear that a system which looks strong on aggregate is creating real harm at the edges where people live.

The best ethical systems treat disagreement as intelligence

One of the clearest signs of maturity is how a company interprets human disagreement with AI. Weak organisations treat disagreement as resistance. Strong ones treat it as intelligence.

When frontline employees contest outputs, they are often surfacing something the system cannot see properly. Missing context. Policy ambiguity. A rare case type. A hidden operational cost. A human signal that does not fit the data structure neatly. If the organisation is wise, it treats those moments as valuable evidence about the limits of the model and the design of the workflow.

That requires a change in posture. Instead of asking, “Why did the employee not trust the system?” leaders should also ask, “What did the employee see that our system or process could not absorb?”

That is a much more serious question. It turns challenge into a source of institutional learning rather than a local inconvenience.

The frontline is where ethical claims become real

Every company can produce a responsible AI statement. Every company can describe review processes and approval structures. But the real meaning of those claims is tested in much simpler moments.

  • A customer says the decision makes no sense.
  • A patient’s situation does not fit the score.
  • A claimant has evidence the workflow did not capture.
  • A support case carries a kind of vulnerability the model was never trained to interpret well.
  • A fraud flag looks statistically plausible but humanly wrong.

In those moments, ethics is no longer a principle. It becomes a live question of whether the employee in front of the issue can act on their judgement and be backed when they do.

That is why frontline challenge rights matter so much. They are where all the lofty language either survives contact with reality or quietly collapses.

Editor’s note: e27 aims to foster thought leadership by publishing views from the community. You can also share your perspective by submitting an article, video, podcast, or infographic.

The views expressed in this article are those of the author and do not necessarily reflect the official policy or position of e27.

Join us on WhatsAppInstagramFacebookX, and LinkedIn to stay connected.

The post The real test of ethical AI is whether a frontline employee can challenge it appeared first on e27.