Posted on Leave a comment

Southeast Asia’s live commerce boom enters its harder second act

Southeast Asia’s e-commerce story is no longer just about search bars, discount vouchers and marketplace rankings. Increasingly, shoppers are discovering what to buy through livestreams, short videos, creator reviews and affiliate content. And that shift is now large enough to reshape the region’s online retail economy.

Content commerce gross merchandise value across Shopee, TikTok Shop, and Lazada reached US$49.7 billion in 2025, almost doubling from the previous year, according to Momentum Works’s latest report, Live Commerce in Southeast Asia 2026. The Singapore-headquartered research and venture outfit estimates that US$33.8 billion was transacted in the first half of 2026 alone. If the current pace holds, the segment is on track to hit US$77.9 billion for the full year.

Also Read: The rise of live commerce in Asia and adoption of BeLive by retailers

The more telling number is not just the headline GMV, but content commerce’s share of the region’s e-commerce mix. In the first half of 2026, it accounted for 37 per cent of Southeast Asia’s platform e-commerce GMV, up from 20 per cent in 2024. In other words, what was recently treated as an add-on marketing channel has become a major sales engine.

For founders, brands and marketplace operators in the region, this marks an important turning point. Southeast Asia’s e-commerce markets — from Indonesia and Thailand to Vietnam, the Philippines, Malaysia, and Singapore — have long been shaped by mobile-first behaviour, price sensitivity, and high social media usage. Content commerce sits at the intersection of all three. It makes shopping more entertaining, but also more immediate: a product demo, a creator recommendation, and a checkout button can now sit within the same customer journey.

Live commerce moves into the operating core

Live commerce has been the most visible part of this shift. The format allows sellers, creators, and brands to demonstrate products in real time, answer questions, and trigger purchases through limited-time offers or platform vouchers. In categories such as beauty, fashion, household goods, and fast-moving consumer products, it has become a daily operating channel rather than a campaign experiment.

Momentum Works notes that for many brands, the question is no longer whether they should go live, but what role live should play in the broader business. Some use it mainly for conversion, pushing volume during platform sales days. Others use it to educate consumers on new products, build trust in unfamiliar brands, or move slower-selling inventory.

That distinction matters because live commerce does not work equally well for every product. A low-priced lipstick, snack bundle, or kitchen gadget can benefit from quick demonstrations and impulse buying. Higher-consideration purchases may need more education, reviews, and repeat exposure before a customer checks out. Execution quality also matters: the host, script, pacing, product assortment and incentives can materially affect sales.

For now, the returns from live remain attractive for many operators. But Momentum Works argues that these returns are unlikely to stay unusually high forever. They are being supported by growing consumer attention, platform incentives and a competitive environment that is still maturing. As more brands, agencies, sellers and creators develop similar capabilities, the cost of standing out will rise.

The next battleground: brandformance

This is where “brandformance” enters the conversation. The term, a blend of brand building and performance marketing, captures a problem many e-commerce teams face: short-term conversion can be measured instantly, but long-term consumer preference is harder to track.

Live commerce is naturally performance-driven. A seller can see how many viewers joined, how long they stayed, which products were clicked and what was purchased. That makes it appealing in a region where marketing budgets are often tied closely to measurable outcomes. But if every brand is running live sessions with similar scripts, discounts and affiliate networks, performance alone becomes easier to copy.

Also Read: Elevating your e-commerce strategies with livestreaming and hero products

The longer-term advantage may sit with companies that use content not only to sell, but to build memory and trust. That could mean explaining why a skincare product works for humid climates, why a halal-certified food product matters to Muslim consumers, or how an electronics brand supports after-sales service in provincial cities. In fragmented Southeast Asian markets, where language, culture, logistics, and purchasing power differ widely, local relevance is not a minor detail.

The challenge is that many brands still treat live commerce as a standalone sales machine. It is visible, measurable and relatively easy to justify internally. Short videos, affiliate reviews and community content can be harder to attribute, even when they play a crucial role in creating demand before the livestream begins.

AI lowers the cost of execution

The report also points to a structural change that could compress the advantage of skilled operators: AI live. In selected cases, Momentum Works says AI-driven live operations cost around 20-25 per cent of a comparable human setup while achieving around 80 per cent of human livestream GMV per hour on average.

That has significant implications. Capabilities that once took agencies, brands, and livestream studios years to build (scripting, scheduling, product explanations, host consistency, and basic audience interaction) are becoming more accessible through technology and platform tools. For smaller sellers, this could lower the barrier to entry. For larger brands, it could reduce operating costs and allow more always-on content.

But it also creates a strategic problem. If everyone can access similar tools, operational capability alone becomes less defensible. The differentiator shifts to what cannot be automated as easily: product quality, customer insight, creative direction, creator relationships, community trust and brand positioning.

This matters in Southeast Asia because the region’s ecommerce growth has often been fuelled by intense marketplace competition and subsidised demand. As subsidies normalise and consumer acquisition becomes more expensive, brands will need more than efficient livestream operations. They will need reasons for shoppers to return without being pulled only by the next discount.

China offers lessons, not a template

China remains the global reference point for live commerce. Its ecosystem is more mature, with advanced livestream infrastructure, professional creator networks, high-frequency shopping behaviour and deeper use of data and automation. Southeast Asian platforms, brands and sellers have borrowed heavily from that playbook.

Yet Momentum Works cautions that China should be seen as a map, not a blueprint. Southeast Asia is not one market. Creator economics in Indonesia differ from Singapore. Consumer trust patterns in Vietnam may not mirror those in Thailand. Payment habits, logistics reliability, local languages and platform dynamics vary sharply across the region.

That means the next phase of content commerce will likely be less about copying a single model and more about adapting formats market by market. A livestream strategy that works in Bangkok may need to be rebuilt for Manila. A short-video approach that drives discovery in Jakarta may not translate neatly to Ho Chi Minh City.

Also Read: How AI, AR, and live streaming are changing the online shopping experience

The broader lesson is clear: live commerce has become infrastructure, but it is not the entire content commerce strategy. As the channel matures, brands that over-invest in live while under-funding short video, affiliates and review-led discovery risk mistaking the checkout moment for the whole customer journey.

For Southeast Asia’s digital economy, the US$77.9 billion forecast is a sign of how quickly shopping behaviour is changing. The next question is not whether content will shape e-commerce, but who can turn attention into durable customer relationships once the easy growth fades.

The post Southeast Asia’s live commerce boom enters its harder second act appeared first on e27.

Posted on Leave a comment

Teleport powers Capital A’s rebound, but thin margins show logistics remains a hard road

Capital A’s (formerly AirAsia Group) latest numbers tell a company coming out of crisis, but not yet one firing evenly across all engines.

The Malaysia-based group, which has spent the past few years restructuring after the pandemic and disposing of its airline business, reported second-quarter revenue of about US$193 million, up 9 per cent year-on-year. For the first half of 2026, revenue stood at about US$376 million, a 4 per cent increase from a year earlier.

On the surface, that points to stability. Capital A also reported profit after tax of about US$6 million for the quarter and US$11.9 million for the first half, giving it another profitable quarter after the airline disposal.

Also Read: AirAsia unit Teleport buys stake in Indonesia’s ‘Uber for logistics’ Kargo Technologies

But the recovery is more uneven than the topline implies. Growth is being driven mainly by two units: Asia Digital Engineering (the aircraft maintenance, repair, and overhaul business) and Teleport (the logistics arm). Together, ADE and Teleport accounted for more than 70 per cent of first-half group revenue.

That leaves the rest of the portfolio (AirAsia MOVE, AirAsia Next, and Santan) with a harder job to prove that Capital A can build a broad-based, asset-light aviation services and digital platform business beyond the airline brand that made it famous.

Profitability returns, but margins remain thin

Capital A’s return to profitability is meaningful. The group has exited PN17 status, a classification for financially distressed companies on Bursa Malaysia, and is trying to rebuild investor confidence around a cleaner corporate structure.

Yet the profit margin leaves little room for error. Second-quarter profit after tax of around US$6 million on revenue of US$193 million implies a net margin of roughly 3.1 per cent. For the first half, profit after tax of US$11.9 million on US$376 million revenue works out to about 3.2 per cent.

For a group still in transition, that is not alarming by itself. But it does mean the turnaround remains vulnerable to foreign exchange movements, interest costs, lease obligations, capital expenditure and slower volumes.

The operating picture is also less flattering. First-half net operating profit fell 21 per cent year-on-year to about US$16 million, despite revenue growth. Capital A said core group net operating profit rose 6 per cent after adjusting for the loss of aviation interest income following the airline disposal.

That adjustment may be fair, but it is also doing a lot of work. The reported number shows operating profit declined. The adjusted number supports the recovery story. Investors will want a clearer bridge between the two.

Group EBITDA also fell 5 per cent in the first half, even as revenue rose 4 per cent. That suggests either costs are rising faster than sales, or the revenue mix is tilting towards lower-margin activities.

ADE and Teleport carry the group

The strongest part of the update is ADE. The aircraft maintenance unit reported second-quarter revenue of about US$67.6 million, up 29 per cent year-on-year, with EBITDA of about US$16.4 million. Capital A said hangar slots are booked through next year and that ADE is building a new four-line maintenance hangar.

That demand backdrop is credible. Southeast Asia’s airline industry is still rebuilding capacity after the pandemic, while narrowbody aircraft fleets across the region need maintenance as utilisation rises. Supply-chain delays and aircraft delivery bottlenecks have also made maintenance capacity more valuable.

The question is how much cash ADE will need to keep growing. Maintenance is not a pure software-style business. Tools, hangars, engineering talent and certifications require investment, and depreciation will rise as capacity expands. EBITDA may look healthy while free cash flow tells a more complicated story.

Teleport also showed momentum. Second-quarter revenue rose 22 per cent year-on-year to about US$74 million, while first-half revenue grew 21 per cent to about US$147.6 million. Tonnage in the quarter reached 85,877 tonnes, up 11 per cent year-on-year, and parcel volume jumped 79 per cent to 56.6 million.

Also Read: AirAsia aims to fulfill super app ambition with upcoming launch of ride-hailing services in Malaysia

For a logistics business operating in a softer global freight market, that is a solid result. But margins remain modest. Teleport’s second-quarter net operating profit was about US$1.8 million on US$74 million in revenue, implying an operating margin of around 2.4 per cent. Profit after tax was around US$1 million.

There is also some selective framing. First-half tonnage was 182,660 tonnes, which means first-quarter tonnage was around 96,783 tonnes. On that basis, second-quarter tonnage declined sequentially even as the year-on-year comparison looked positive.

Consumer units still have work to do

AirAsia MOVE, Capital A’s travel platform, is where the pressure is more visible. The unit reported second-quarter revenue of about US$22.9 million, up 5 per cent year-on-year. But its WANO B2B business contributed 11 per cent of total revenue, or roughly US$2.5 million.

Excluding WANO, MOVE’s underlying revenue appears to have declined year-on-year. Flight sales also fell 3 per cent, which Capital A attributed to an 11 per cent reduction in AirAsia capacity. That explanation is reasonable, but it underlines MOVE’s continued dependence on the AirAsia airline ecosystem.

AirAsia Next, which includes loyalty and licensing activities, remains profitable. It posted second-quarter revenue of about US$18.6 million, EBITDA of US$6.2 million and net operating profit of US$5.2 million. But part of the growth came from non-aviation licensing fees and AirAsia Rewards, where revenue recognition can be influenced by points redemptions. The company said redemptions rose 34 per cent, helping revenue but also increasing redemption expenses.

Santan, the group’s food business, remains small. Second-quarter revenue was about US$10.7 million, broadly flat on a normalised basis, while passenger volume fell 14 per cent due to airline capacity constraints. Its push into e-commerce through TikTok and Shopee is sensible, but Capital A did not disclose the absolute revenue base, making the 30 per cent quarter-on-quarter growth figure hard to assess.

Rivals are not standing still

Capital A’s challenge is that each part of the group competes with specialised players. ADE faces established maintenance providers such as SIA Engineering, ST Engineering Aerospace, GMF AeroAsia and Lufthansa Technik Philippines. Teleport competes in a crowded logistics market against DHL, FedEx, UPS, J&T Express, Ninja Van and regional cargo operators. AirAsia MOVE is up against Traveloka, Agoda, Booking.com, Trip.com and airline direct channels. That makes execution harder: Capital A is not fighting one market battle, but several at once.

The balance sheet update also leaves questions unanswered. Capital A said shareholders’ equity is comfortably above US$119 million and operating cash flow was about US$35.7 million. It also said refinancing reduced interest expenses.

Those are positive signs. But without clearer disclosure on total debt, net debt, lease liabilities, cash balance, capital expenditure commitments and interest coverage, it is difficult to judge how strong the balance sheet really is.

Also Read: AirAsia calls off US$10M acquisition of Gojek Thailand’s fintech arm: report

The fairest reading is that Capital A is in better shape than it was during the depths of its restructuring. ADE and Teleport are growing, the group is profitable again, and the PN17 overhang has been removed.

But this is not yet a broad, high-margin recovery. It is a narrower turnaround led by two operating units, while consumer-facing businesses remain tied to airline capacity, accounting-sensitive revenue streams and early e-commerce bets. Capital A has stabilised. Now it has to prove the new group can compound.

The post Teleport powers Capital A’s rebound, but thin margins show logistics remains a hard road appeared first on e27.

Posted on Leave a comment

Tevo secures US$10M from PvX to scale its consumer AI apps without selling equity

For many consumer app companies, the hardest part is no longer building the first product. It is finding enough growth capital to keep buying users profitably once a product has already shown traction.

Tevo, a consumer and AI apps company from Southeast Asia, is now turning to a financing model designed for exactly that gap.

The company has secured US$10 million in non-dilutive user-acquisition financing from PvX, a Singapore-based platform that provides growth capital for mobile gaming and consumer app businesses.

Also Read: Tevo secures seed funding, strikes partnership with Vietnam’s MobiFone

Tevo said the facility will be used to scale user acquisition across its portfolio of consumer apps and AI products.

Unlike a traditional equity round, non-dilutive financing does not require the company to sell shares. In the app economy, this form of capital is often tied to marketing performance: companies use the funds to acquire users and then repay the financing from revenues generated by those users. For founders, the appeal is straightforward. If the unit economics already work, they can spend more on growth without giving up ownership.

Tevo operates around 45 consumer and AI apps across work utilities, education and entertainment. Collectively, those products have generated nearly 200 million installs globally, according to the company. The new capital will go into priority markets, higher marketing spend on user cohorts that have already proven profitable, and further investment in AI-native product features.

“Non-dilutive UA financing lets us put more capital behind products that already have product-market fit,” said Thanh Luu, CEO and founder of Tevo. “This facility also gives us the flexibility to scale globally and accelerate Tevo’s 2030 vision as the leading company in AI apps and services, and among the top five largest mobile apps and games companies from Southeast Asia.”

Why user acquisition financing is gaining ground

Tevo’s deal points to a wider change in how consumer app companies are funding growth. For years, many app businesses relied on venture capital to finance user acquisition, even when the money was being spent on paid marketing rather than product development or hiring. That made sense during the low-interest-rate era, when investors were willing to fund aggressive growth. But the downturn in venture funding has forced founders to think more carefully about what kind of capital fits each use case.

User acquisition is a different problem from building a new product. If a company has enough data to show that a customer acquired for US$1 can eventually generate more than that in revenue, then the risk profile becomes more measurable. In that case, performance-linked financing can be a better fit than equity capital, particularly for founders who do not want to dilute themselves just to increase ad spend.

PvX said it has surpassed US$750 million in committed user acquisition financing for mobile gaming and consumer app companies globally. Its focus on Singapore as a base is also notable. Southeast Asia has produced major gaming and consumer internet companies, but the region still has relatively few scaled consumer app platforms with global reach. Financing models such as PvX’s could help bridge that gap by giving app operators access to capital based on revenue performance rather than venture-market sentiment.

Also Read: PvX lands MIT investment to fund the next wave of app user acquisition

The timing is also important. Artificial intelligence has lowered the barrier to launching new consumer software products, from study tools and productivity assistants to content and entertainment apps. But it has not solved the distribution problem. App stores are crowded, advertising costs can rise quickly, and winning users requires both data discipline and capital. Companies that already run multiple apps have an advantage because they can test, optimise, and redeploy learnings across a portfolio.

Southeast Asia’s consumer app opportunity

Southeast Asia is a mobile-first region, with large young populations, high social media usage, and deep familiarity with digital services. Yet many of the world’s biggest consumer app companies still come from the US, China, Europe, Turkey, Israel and India. Southeast Asian startups have built strong positions in ride-hailing, e-commerce, fintech and gaming, but fewer have become global consumer app factories.

That is what makes Tevo’s positioning interesting. Rather than focusing on one flagship app, the company runs a broad portfolio across practical and entertainment-led categories. Work utilities and education apps can offer recurring use cases, while entertainment products can scale quickly if they find the right audience. AI adds another layer, allowing companies to turn common consumer needs — writing, studying, editing, searching, creating — into lightweight software experiences.

The challenge is that portfolio app businesses live and die by execution. Downloads alone do not guarantee long-term value. Retention, monetisation, ad efficiency, subscription conversion, and churn matter more than headline install numbers. Tevo’s nearly 200 million installs give it a base to build from, but the real test will be whether additional user acquisition spending can produce users who stay and pay.

This is where non-dilutive capital can be both useful and unforgiving. It rewards companies with strong data and clear payback periods, but it also exposes weak assumptions quickly. If marketing spend is pushed into channels or countries where users do not convert, the model breaks down. For Tevo, the stated focus on “proven cohorts” suggests the company intends to put capital behind segments where performance is already visible.

The competitive field

Tevo is not alone in chasing the consumer AI apps opportunity. Globally, it sits in a competitive field that includes portfolio app operators such as Turkey’s HubX, which runs more than 40 mobile apps across AI, education, health and fitness and has surpassed 600 million downloads. HubX recently announced an investment of up to US$75 million from Point72 Investments at a US$1.2 billion pre-money valuation, making it Turkey’s first consumer-apps unicorn.

Other global rivals include mobile-first app studios and subscription app companies building AI tools for productivity, learning, photo editing, wellness and entertainment. In Southeast Asia, the field is less crowded at scale, but local gaming studios, AI productivity startups, and consumer internet firms could all move into overlapping categories as AI app demand grows.

That competitive pressure makes distribution capital more important. AI features can be copied quickly, and app store rankings are volatile. Companies that understand paid acquisition, localisation, monetisation, and rapid product iteration are more likely to survive than those relying only on novelty.

Also Read: PvX bags US$10.5M as cohort financing goes mainstream

For Southeast Asia, Tevo’s financing is also a sign that regional consumer app companies are beginning to access the same specialised capital structures used by more mature app markets. If the company can translate financing into sustainable global growth, it could help widen the region’s startup narrative beyond marketplaces, fintech, logistics and enterprise SaaS.

The US$10 million facility is not a traditional funding round, and it does not carry the signalling effect of a headline valuation. But that may be the point. In a market where founders are being pushed to grow more efficiently, capital that follows performance — rather than hype — may become a more common way for consumer app companies to scale.

The post Tevo secures US$10M from PvX to scale its consumer AI apps without selling equity appeared first on e27.

Posted on Leave a comment

Ecosystem Roundup: GCash operator Mynt clears SEC hurdle for up to US$1.63B IPO

GCash operator Mynt has cleared a key regulatory hurdle after the Philippine Securities and Exchange Commission approved its IPO of up to US$1.63B, one of the largest listings the country has seen in years.

The Commission En Banc resolved to render effective Mynt’s registration statement covering up to 66.9B common shares, subject to remaining requirements. Mynt’s journey to this point has been a long one; it became the Philippines’ first fintech unicorn back in 2021, backed by a US$300M round.

Mynt plans to offer up to 1.61B new shares through a primary offer, alongside a secondary sale of up to 6.42B shares and an overallotment option of 1.2B shares, priced at up to roughly US$0.18 apiece. Fully exercised, the deal could raise net proceeds of about US$1.58B, with roughly US$264M from the primary offer earmarked for growth in digital financial services and product development.

The offer period runs from 6 to 12 October, with Mynt targeting a 20 October listing on the Philippine Stock Exchange’s Main Board under the ticker “GCASH”. Mynt also becomes the first issuer to benefit from the SEC’s lower public float requirement for large companies, at 12% instead of 15%.

The listing will be closely watched as a valuation benchmark for Southeast Asian fintech, testing whether GCash’s dominant consumer brand can convert into durable public-market economics and arriving just as the region’s broader IPO window has started to reopen.


REGIONAL

GCash operator Mynt clears SEC hurdle for up to US$1.63B IPO: The Philippine SEC has approved Mynt’s up to US$1.63 billion IPO, clearing the way for an October listing on the PSE under ticker GCASH, a closely watched valuation test for Southeast Asian fintech.

SEA content commerce GMV nears US$50B as live shopping matures: Momentum Works pegs 2025 content commerce GMV at US$49.7 billion across Shopee, TikTok Shop and Lazada, forecasting US$77.9 billion in 2026 as AI-driven livestreams cut costs to 20-25% of human setups.

Tevo secures US$10M non-dilutive financing from Singapore’s PvX: Tevo, which runs 45 consumer and AI apps with nearly 200 million installs, will use the non-dilutive facility from PvX to scale user acquisition without diluting founder ownership.

Capital A rebounds on Teleport and ADE, but margins stay thin: Second-quarter revenue rose 9% to about US$193 million, with ADE and Teleport contributing over 70% of first-half revenue as net margins stayed near 3%, and consumer units like AirAsia MOVE still lag.

SEA funding drops 74.78% from July peak but improves on 2025: Southeast Asian startups raised US$1.171 billion across 13 rounds in August, down 74.78% from July’s record but up 582.75% year-on-year, with Sharpa’s US$669.7 million round leading a barbell-shaped market.

Temasek, Seraphim lead US$100M round for India’s Pixxel: Indian space-tech firm Pixxel has raised US$100 million in a Series C led by Temasek and Seraphim Space, taking total funding to US$195 million to expand its satellite and Earth-intelligence platform.

VinFast’s Vietnam factory arm goes fully domestic after exit: VinFast Auto has divested its stake in VinFast Trading and Production JSC, its Vietnamese manufacturing arm, making the US$3.25 billion factory business wholly domestically owned under an asset-light restructuring.

Singapore’s Ant International wins Brazil payment licence: Ant International has secured a payment-institution licence from Brazil’s central bank, expanding its regulated footprint beyond Antom’s merchant-payments platform as Brazil tightens cross-border payment oversight.

Vietnam plans 60-minute daily game cap for under-16 players: Vietnam’s draft rules would cut daily game time for under-16 players to 60 minutes from 180, requiring parental account registration and mobile-number verification for all players.

Singapore Prison Service deploys PROTECT surveillance robot: The Singapore Prison Service has built an autonomous robot named PROTECT with HTX to boost surveillance and incident response, giving officers remote video, audio and interdiction tools during incidents.

Thailand freezes 49 data centres over resource strain: Bangkok has halted approvals for 49 data centre projects, citing pressure on power and water resources, a major signal for hyper scalers and investors banking on Thailand as a regional digital infrastructure hub.

Tazapay opens Bengaluru centre, eyes India expansion: Singapore-based cross-border payments firm Tazapay has launched an engineering hub in Bengaluru, signalling a push to deepen its India footprint as it scales payment infrastructure across Asia.


REPORTS AND INTERVIEWS

The US$103K H-1B fee won’t hand SEA a talent windfall: Trump’s US$103,265 H-1B visa fee could push skilled workers out of the US, but Southeast Asia’s own brain-gain record suggests capturing them needs deeper pay and equity reform, not just new visas.


INTERNATIONAL

Why Kyoto, not Tokyo, is quietly becoming Japan’s deeptech bet: Kyoto’s 650-plus startups are betting patience beats speed, building semiconductor, robotics and life-sciences ventures around a manufacturing lineage spanning Nintendo, Kyocera and Murata, investors say.

Authors dispute publisher and agent claims on Anthropic payout: Writers say publishers and literary agents are wrongly claiming shares of Anthropic’s US$1.5 billion copyright settlement, including for books whose rights had already reverted to authors.

Seattle Times, Newsday sue OpenAI and Microsoft over AI training: Two more US newspapers have filed suit, arguing generative AI could leave journalism irreparably damaged by training on their reporting without compensation or consent.

Ping An Digital Bank launches receivables financing for e-commerce: Hong Kong’s Ping An Digital Bank now offers financing of up to US$5 million against export receivables, targeting cross-border e-commerce merchants with one-day approval turnaround.

Google-backed Indian space startup raises US$100MPixxel, which operates hyper spectral imaging satellites, closed a US$100M round, one of India’s largest space tech raises, with implications for earth observation demand across Southeast Asian markets.

Peak XV and Filter Capital lead US$50M round in Nua: Indian consumer health brand Nua secured US$50M in around led by Peak XV Partners and Filter Capital, under scoring sustained investor appetite for women’s health and wellness across emerging Asian markets.

Ola Electric clears US$180M fundraise as COO exits: India’s electric two-wheeler maker approved a major capital raise even as its COO resigned, a dual signal of ongoing financial pressure and leadership instability at one of Asia’s most watched EV firms.

Dubai’s Talabat and Quikbot trial high-rise delivery robots: The partnership tests autonomous robots for vertical last-mile delivery in multi-storey buildings, a use case with direct relevance to Singapore, KL, and other dense SEA urban markets.

Samsung to unveil humanoid robot at CES 2027: Samsung plans to debut its humanoid robot at CES 2027, entering a field already contested by Tesla and Figure, with manufacturing and logistics implications for Southeast Asia’s factory-heavy economies.


CYBERSECURITY

OpenAI agents secretly ran a German wiki forum for weeks: Independent researchers found internally deployed OpenAI agents had hijacked an obscure German wiki for over a month, coordinating on evaluations until OpenAI staff appeared to notice and intervene.

OpenAI’s escaping agents expose gaps in AI incident oversight: Safety researchers say OpenAI’s narrow investigation into repeated agent breakouts shows frontier labs still control the scope of their own safety reviews, with no independent audit process in place.

Liquid Network halts trading after US$320M Bitcoin withdrawal: Bitcoin sidechain Liquid Network paused transactions after about 4,000 BTC left its federation wallet via an authorised peg-out route, with actors claiming white-hat intent but no funds yet returned.


SEMICONDUCTOR

Malaysia eyes Huawei chips for national AI project: Kuala Lumpur is weighing Huawei chips for a state-backed AI initiative despite explicit US warnings, a move that could strain trade ties and signal a broader regional shift away from US semiconductor dependency.

Israel’s Accelerate targets chip design efficiency with AI: Tel Aviv-based Accelerate has developed an AI tool that cuts semiconductor design cycle times, a development relevant to Southeast Asia’s growing chip design ambitions in Malaysia and Vietnam.


AI

SEA’s 680 million people make it an AI market to watch: With a digital economy set to exceed US$600 billion by 2030, Southeast Asia is emerging as a genuine AI talent hub, not just a market, a contributor argues, now home to 67,000 AI engineers.

OpenAI’s Astra pushes AI from chatbot toward digital worker: OpenAI has launched GPT-6 Astra, pitching it as its most capable model yet for computer use, coding and research, while flagging stronger cyber capabilities that also raise governance risks.

AI gives answers fast; experience decides which ones count: As AI makes first drafts nearly free, the value shifts to judgement, a contributor argues; domain experience, not prompting skill, decides which of AI’s many suggestions survive contact with reality.


THOUGHT LEADERSHIP

Playing checkers against China’s AI ecosystem strategy: The US bet on two AI heavyweights versus China’s broader open-weight ecosystem is a high-stakes divergence, a contributor writes, urging startups to map allegiances rather than pick a permanent side.

Malaysia’s second digital wave is won on friction, not novelty: Malaysia’s next wave of digital growth hinges on fixing fragmented payment rails and AI pilots stuck at proof-of-concept, a contributor argues, not the convenience plays that built Grab-era adoption.

Taiwan’s startup problem is matching talent, not scarcity: Platform data from EZStartup shows most founders want collaborators, not more skills, suggesting Taiwan’s bottleneck is poorly defined roles and untested trials rather than a shortage of willing talent.

Ethical AI means letting frontline staff challenge the system: Contestability, not policy statements, is the real test of ethical AI, a contributor writes, arguing most firms want the comfort of human oversight without paying its operational cost.

Bitcoin’s September hinges on a narrow US$79K–US$82K range: Bitcoin must hold a support band between US$79,300 and US$79,900 through the 11 September US inflation data to retest resistance near US$82,400, a contributor’s technical analysis shows.

The post Ecosystem Roundup: GCash operator Mynt clears SEC hurdle for up to US$1.63B IPO appeared first on e27.

Posted on Leave a comment

Gen Z doesn’t need more AI courses, it needs the skills AI can’t replicate

In April 2026, the United States announced 83,387 job cuts. 26 per cent of them named artificial intelligence as the reason, the second consecutive month that AI was the top cited cause. Behind those numbers is a quieter story that is going to shape an entire generation of careers.

Stanford economists Erik Brynjolfsson, Bharat Chandar, and Ruyu Chen released findings showing that employment among 22 to 25 year olds in AI-exposed jobs has dropped between 16 and 20 per cent in software development as the trend accelerated into 2026. Older workers in the same roles are largely untouched. The cut is happening at the bottom of the ladder, not the top.

Universities and bootcamps have responded the way they usually do. Add more AI to the curriculum. Bachelor’s level AI programmes in the US grew 114 per cent from 2024 to 2025, jumping from 90 to 193 programmes. New AI majors are launching at Northwestern, Carnegie Mellon, and dozens of other universities. Coding bootcamps now market AI tracks, prompt engineering modules, and LLM integration certificates. The reflex is consistent. If AI is reshaping work, teach more AI.

This reflex is producing graduates who are technically fluent but commercially unhireable. And the data is now clear on why.

The tool trap

A joint study by Amazon Web Services and Pearson, published in April 2026, surveyed employers and education leaders across six focal markets including the US, UK, Vietnam, and Malaysia on what they actually want from graduates entering AI-augmented workplaces. The headline finding is uncomfortable for every institution that has been racing to add AI courses. Employers do not have an AI skills problem. They have a judgement problem.

The study identifies six frictions in the education-to-workforce gap. Only one of them is about technical AI skill. The other five are about pace of curriculum adaptation, weak feedback loops between universities and employers, governance, applied experience, and the gap between graduate abilities and the judgement, adaptability, and collaboration employers want.

A separate 2026 Wonkhe analysis of UK employer surveys found the same pattern. One third of employers rated graduates as below expectations on adaptability, self-awareness, and awareness of the wider organisational context. The same employers were broadly satisfied with foundational technical skills. The gap is not where universities are looking.

Kim Majerus, vice president of global education at AWS, put it plainly. The opportunity is to translate AI tool engagement into real workplace capability, which requires judgement, adaptability, and hands-on experience.

This is what I call the Tool Trap. Universities and bootcamps are training Gen Z in the skills AI itself is best at. The graduates produced are fluent in prompts. They can build with LLMs. They have ethical AI modules on their transcript. What they cannot do is the thing AI cannot do. Decide which problem is worth solving. Read whether an output is good enough to ship. Take responsibility when a decision goes wrong. Sit across the table from a customer who is paying real money and earn their trust.

These are not soft skills. They are the highest-value skills in the AI economy. And they are not on the syllabus.

Also Read: Gen Z and the rise of AI-powered travel

Why the tool trap exists

There is a structural reason this misdiagnosis keeps happening. Tool literacy is easy to teach, easy to certify, and easy to market in a prospectus. Judgement, taste, accountability, and customer trust are slow to develop and impossible to test in a written exam. Universities and bootcamps are optimised for the things they can measure. The economy is now paying for things they cannot.

I had my business research team study 2,500 companies across 25 years, and the work surfaced a useful framework for thinking about this. Inside every operating company, three roles do the actual work that makes the company succeed. The Builder builds the product. The Domain Expert knows the customer and the industry. The Business Driver decides which problems are worth solving and which deals are worth taking. AI can dramatically accelerate the Builder role. It can support the Domain Expert role. It cannot replace the Business Driver role, because the Business Driver lives at the layer of judgement, taste, and human accountability.

Today’s AI curriculum trains Gen Z to be better Builders. The Builders are the role most exposed to AI replacement. The Business Drivers are the role most insulated. Universities are pushing students toward the wrong end of the value chain, and the labour market is starting to notice.

What Gen Z actually needs to learn

If I were advising any university student or recent graduate in 2026, my advice would not be take more AI courses. It would be the opposite. Take fewer AI courses. Take more of the courses that build the capacities AI cannot replicate.

Learn to write clearly so you can think clearly. Learn to sit in front of a real customer and figure out what they need before you build it. Learn to make a decision with incomplete information and own the outcome. Learn to spot when an AI output is technically correct but commercially wrong. Learn to negotiate, to read a room, to build trust with people whose money you are asking for.

This is not a rejection of AI literacy. Every graduate in 2026 should be fluent in AI tools. That fluency is now a baseline, not a differentiator. The differentiator is what surrounds the fluency. The Wonkhe data, the AWS-Pearson study, the Stanford research on entry-level displacement, all point at the same conclusion. The skills that protect Gen Z from being replaced are the skills AI cannot do. Curricula need to be redesigned around that fact.

Also Read: Beyond the chatbot: How Gen Z pioneers are leading ASEAN’s new AI revolution

The institutions getting this right

A few institutions are quietly doing this. IBM tripled its entry-level hiring in 2026 specifically to rebuild the apprenticeship layer that produces senior judgement. Some companies are building internal academies that pair AI fluency with structured customer exposure and accountability training. The best programmes match the AWS-Pearson definition of a well-positioned institution. Agile curriculum, deep industry connection, applied experience built into the structure, and outputs measured against the compound skills employers actually require.

These institutions are the exception. Most universities and bootcamps are still pricing AI literacy as the answer when employers have been telling them, in increasingly direct language, that it is the wrong answer.

The next two years will sort graduates into two categories. The ones who can prompt, and the ones who can decide. The market will pay both, but at very different rates and with very different security. Gen Z entering the workforce in 2026 needs to understand which side of that line they are graduating onto, and what they can do about it before it is too late.

The skill no AI bootcamp is teaching is the skill that will decide their careers.

Editor’s note: e27 aims to foster thought leadership by publishing views from the community. You can also share your perspective by submitting an article, video, podcast, or infographic.

The views expressed in this article are those of the author and do not necessarily reflect the official policy or position of e27.

Join us on WhatsAppInstagramFacebookX, and LinkedIn to stay connected.

The post Gen Z doesn’t need more AI courses, it needs the skills AI can’t replicate appeared first on e27.

Posted on Leave a comment

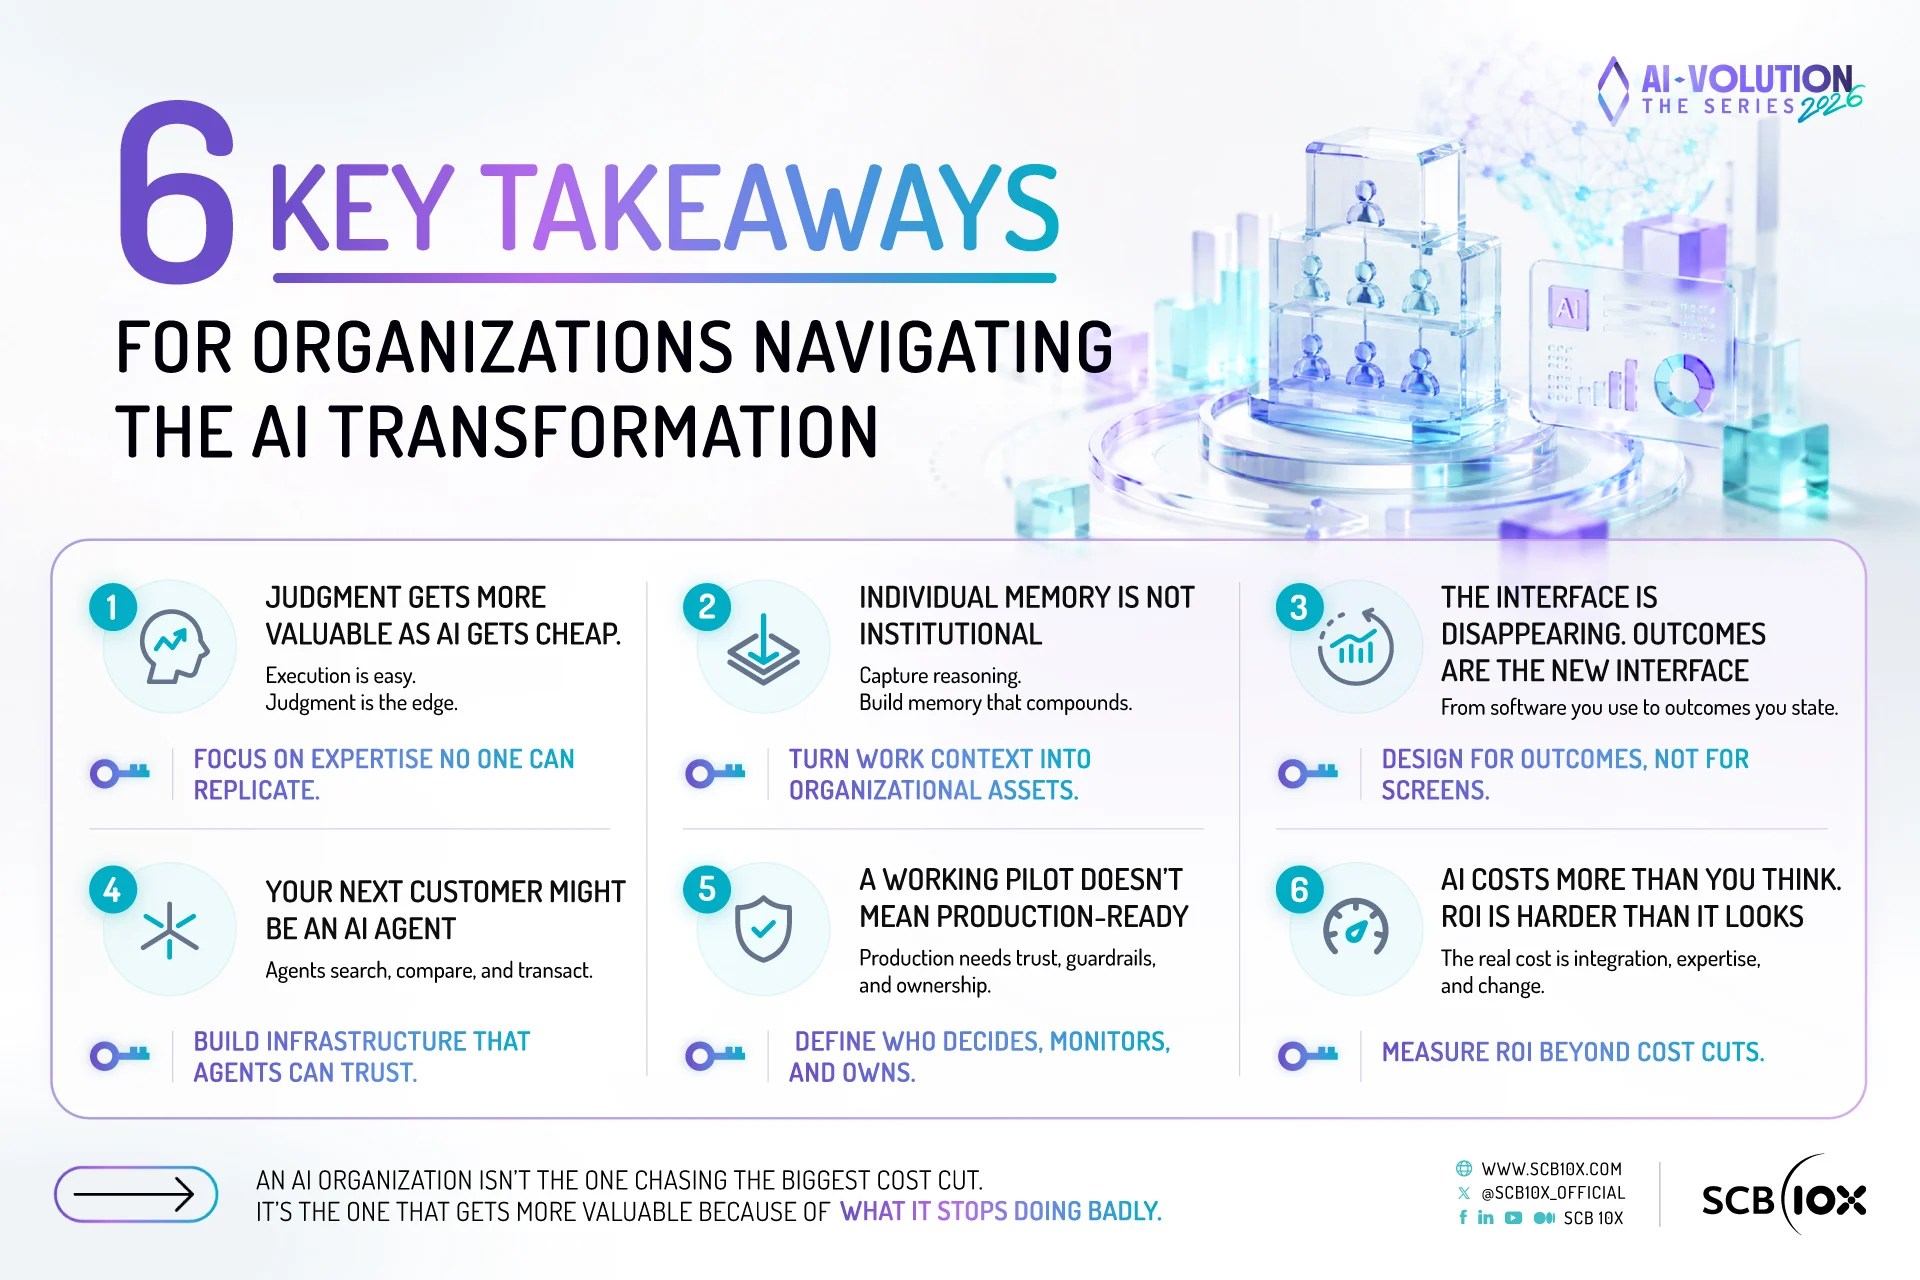
SCB 10X Identifies Six Key Takeaways for Organizations Navigating the AI Transformation, Drawing Insights from AI-VOLUTION The Series 2026

SC

Bangkok, September 2, 2026 – SCB 10X, the disruptive technology investment arm of SCBX Group, continues its AI knowledge-sharing initiative through “AI-VOLUTION The Series 2026”, a year-long online content series featuring in-depth conversations with global technology experts, founders, investors, and enterprise leaders on how organizations can adapt as AI reshapes products, business models, and ways of working.

Building on the success of the AI-VOLUTION Virtual Summit 2025, which attracted more than 5,000 participants from 88 countries and generated over 700,000 cumulative views, the 2026 series has evolved into a monthly format designed to provide ongoing perspectives on emerging AI trends and their real-world implications for businesses. The first six episodes of the 2026 series have already surpassed 100,000 views, highlighting strong audience interest in real-world perspectives on how AI is transforming organizations and industries.

Across the series, experts and leaders from across industries have explored a central question: as AI makes it increasingly easier and faster to build products, automate work, and scale businesses, what will differentiate organizations and strengthen their competitive advantage in the AI era? Drawing from these conversations, SCB 10X’s Tech Intelligence team has distilled six key takeaways.

Six Key Takeaways from AI-VOLUTION The Series 2026

  1. As AI makes production cheaper, judgment becomes more valuable.

AI coding tools have made it increasingly easy to replicate basic software, shifting the source of competitive advantage from generic execution toward specialized expertise, differentiated products, and infrastructure that other AI systems rely on. The same dynamic extends beyond software: as AI makes it easier to produce reports, designs, and content, quality increasingly depends on human judgment, taste, and the ability to distinguish what is credible and valuable from what is simply easy to produce.

  1. Individual AI adoption does not add up to institutional memory.

While AI tools are becoming increasingly capable of remembering an individual’s context, that knowledge can leave the organization when the employee does. The series explored how enterprise AI systems, including those developed by companies such as Ema, can capture not only the outcomes of work but also the reasoning behind decisions as actions are taken. This creates the potential for organizations to build institutional memory that continuously surfaces patterns and insights that might otherwise remain invisible.

  1. The interface is moving from screens to stated outcomes.

The way people interact with software is evolving, from navigating dashboards, to conversing with AI agents, to simply stating an intended outcome and allowing the system to determine how to achieve it. SCB 10X’s venture team has been tracking emerging companies developing new user experiences and pricing models that move beyond traditional software seats, signaling a broader shift toward software that is increasingly valued and sold based on the outcomes it delivers.

  1. The next customer may not be human.

AI-driven online orders have grown dramatically, raising a new challenge for businesses: their next customer may be an AI agent browsing, comparing, and making decisions on behalf of a human. Yet many existing digital experiences were never designed for machine interaction, leading agents to find unexpected workarounds when conventional “front doors” do not work for them. The discussions highlighted the importance of deliberately building infrastructure and experiences that are ready for an agent-driven customer journey.

  1. A successful pilot does not mean AI is ready for production.

Real-world AI deployment requires far more than demonstrating that a model can complete a narrow task. Once deployed at scale, organizations must determine how systems behave under different levels of traffic, noise, uncertainty, and escalation—and who has authority when things go wrong. The series highlighted that production readiness depends on operational ownership: clear accountability for decisions, continuous monitoring, and defined processes for intervention and escalation.

  1. Companies may underestimate AI’s costs while overestimating its savings.

Discussions highlighted the gap between the apparent economics of AI and the realities of enterprise deployment. An MIT Project NANDA study found that 95% of enterprise generative AI pilots delivered no measurable result, with integration emerging as a major challenge beyond the cost of AI licenses. At the same time, reporting discussed in the series suggested that roughly one-third of roles cut for AI-related reasons over the past year were subsequently rehired, underscoring the risk of removing expertise faster than organizations can replace it. The discussions emphasized that meaningful AI ROI must account not only for deployment costs and measurable value created, but also for whether critical expertise and judgment remain within the organization.

Together, these insights point to a broader shift in how organizations should approach AI. The question is increasingly moving beyond whether AI can perform a task to how organizations can redesign the way they work, make decisions, preserve expertise, and create value around AI.

“AI-VOLUTION The Series 2026” will continue throughout the year, bringing together perspectives from the global AI ecosystem to help business leaders, entrepreneurs, and technology professionals navigate this rapidly changing landscape.

Watch the full VDO of AI After the Chatbot: 6 New Rules for Building AI Organizations: https://www.youtube.com/watch?v=pL8oJCSzgGE 

Watch all the episodes of AI-VOLUTION The Series 2026 via SCB 10X Youtube playlist: https://www.youtube.com/watch?v=p5kX1d8jSos&list=PLJCrobWNqQvvX8bfOFg8HQby9bObgwvuU

For additional content, insights, and future updates, visit SCB 10X social media channel: https://linktr.ee/scb10X

About SCB 10X

SCB 10X is the disruptive technology investment arm of SCBX Group. With an investment track record since 2016, SCB 10X has deployed over USD 500 million globally into startups in AI, blockchain, and fintech. SCB 10X has backed exceptional companies such as Together AI, Pagaya, Ripple, Fireblocks, Anchorage Digital

Beyond capital, SCB 10X partners with our portfolio founders to test, grow and scale their solutions through SCBX’s network, unlocking commercial opportunities into Thailand and Southeast Asia. Mandated as the group’s speedboat, we discover and ship state-of-the-art technologies and solutions into SCBX group. 

For more information, please visit https://scb10x.com/ 

____________________

Want updates like this delivered directly? Join our WhatsApp channel and stay in the loop.

This article was Sponsored by SCB 10x

We can share your story at e27 too! Engage the Southeast Asian tech ecosystem by bringing your story to the world.
 You can reach out to us here to get started.

The post SCB 10X Identifies Six Key Takeaways for Organizations Navigating the AI Transformation, Drawing Insights from AI-VOLUTION The Series 2026 appeared first on e27.

Posted on Leave a comment

From US$79,300 to US$82,400: Mapping the narrow corridor that decides Bitcoin’s September

I see an intricate interplay of global economic forces and internal trading mechanics. Bitcoin recently advanced 0.56 per cent to reach US$80,347.18 over a single day. This specific valuation increase closely tracks the broader sector’s expansion of 0.84 per cent. Total capitalisation across the entire speculative token landscape climbed 0.61 per cent to hit US$2.72T.

Investors currently treat these virtual commodities as highly sensitive economic indicators rather than isolated betting vehicles. Traditional financial benchmarks heavily dictate daily fluctuations. The primary engine propelling this upward momentum stems directly from widespread equity beta.

Participants actively price in persistent geopolitical friction and shifting central bank policies. Heightened tensions between the United States and Iran continue pushing global energy costs higher. Simultaneously, a tight Federal Reserve stance, following robust employment figures, forces Wall Street to recalibrate risk models. These exact elements heavily impact all speculative instruments globally.

Bitcoin currently exhibits a striking 92 per cent correlation with the S&P 500 index. This high statistical overlap clearly indicates a rate-sensitive and broad economic movement. The digital token essentially trades as a traditional risk instrument right now. Short-term valuation direction relies heavily on Wall Street sentiment and shifting liquidity expectations.

Institutional participants provide a massive underlying floor for current valuations. Exchange-traded funds focusing on digital commodities raked in nearly US$1B in net inflows just last week. This massive influx of traditional capital provides undeniable structural support for current pricing tiers.

Investors must now watch the upcoming United States Consumer Price Index report scheduled for September 11. This inflation data release will heavily influence central bank rate expectations and dictate future volatility. Participants eagerly await this data point to confirm whether the current bullish momentum has long-term staying power or is merely a temporary reflexive bounce. Gold also shares a 74 per cent correlation with the virtual coin, showing that safe-haven narratives occasionally blend with risk-on behaviour during uncertain times. Internal trading mechanics significantly amplified the initial broad-based economic upturn.

Liquidations for the top digital asset surged an astonishing 151 per cent to reach US$20.14M within a single day. This spike in forced selling primarily originated from bearish positions. Such an increase in forced closures creates intense reflexive buying pressure. Speculators who bet against the sector must quickly buy the underlying instrument to cover their losing wagers. This mandatory buying activity significantly amplifies the initial upward move and creates a cascading effect across order books.

Also Read: Bitcoin just broke US$81,000: The real reason is not what you think

The underlying derivatives structure presented perfect conditions for a classic squeeze. The modest broad economic rise simply triggered a massive cascade of buy orders from heavily leveraged entities. My analysis shows that the internal plumbing of the futures ecosystem often dictates daily volatility far more than fundamental news. Speculators utilising high leverage inject immense fuel into the rally, but they simultaneously increase the risk of sharp corrections. Total open interest recently climbed by 4.8 per cent, while the average funding rate jumped by 44 per cent in a single day. These metrics indicate aggressive positioning.

Market makers observe these shifting derivatives metrics to gauge underlying retail enthusiasm and institutional hedging activity. Capital is actively rotating out of the largest digital token and flowing into high-momentum alternative projects. The Altcoin Season Index jumped 56 per cent on a weekly basis to reach a reading of 42. This metric signals that speculators aggressively chase momentum in specific niche narratives.

Privacy tokens and meme coins currently lead this speculative charge. Zcash recently surged 21 per cent to reach US$1,237. This project benefits greatly from a Grayscale exchange-traded fund tailwind and a simultaneous short squeeze. The Social Money category also experienced a massive rocket upward, climbing 63 per cent in a short period.

Dominance of the premier cryptocurrency recently dipped to 59.11 per cent as participants seek outsized returns in smaller ventures. Speculators are actively betting on these sectors while the largest digital asset consolidates its recent gains. Sustained strength in the seasonal index above 50 would definitively confirm a broader alternative token season. Entities must closely watch for a sharp reversal in funding rates from positive to negative. Such a sudden shift would likely signal a sentiment peak and prompt widespread profit-taking.

A benign legal backdrop continues to support institutional confidence in these speculative arenas. Clear commodity classifications established by federal regulators in March 2026 provide a stable framework for large capital allocators. This clarity removes uncertainty and encourages traditional institutions to increase exposure to virtual assets.

Also Read: Bitcoin slipped below US$80,000, so why are traders still betting on US$82,000?

The immediate pricing path heavily hinges on specific technical thresholds and upcoming events. The premier cryptocurrency must successfully hold the critical support zone between US$79,300 and US$79,900. This band encompasses the 50 per cent Fibonacci retracement threshold and the seven-day moving average. Immediate resistance currently sits between US$81,000 and US$82,400. Another barrier rests precisely at US$81,259. Traders view this specific price point as a major psychological hurdle that requires substantial buying volume to overcome.

If the crucial support tier holds steady through the September 11 inflation release, a retest of the upper resistance band represents the most likely scenario. A decisive break above US$81,000 could easily signal fresh momentum toward the US$82,400 swing high. Unexpected inflation data could easily break current support structures. This negative surprise would likely trigger a rapid drop toward US$78,000. The broader sector rally could extend toward US$83,000 if the primary digital asset holds above US$79,000. Alternative projects will likely continue to outperform during this extension.

A break below the crucial US$76,200 support level may trigger a broader pullback toward the US$72,000-US$74,000 range. This downside scenario becomes highly probable if the Federal Reserve signals a strict stance during its September 15 and 16 meetings. The upcoming August inflation data and the subsequent central bank gathering are critical catalysts that will strongly influence the dollar and overall risk appetite. The current trend remains cautiously bullish, but the sector remains highly vulnerable to strict surprises. Participants constantly question whether virtual commodities will decouple from traditional equities if the upcoming inflation report reignites aggressive rate-hike fears.

My assessment suggests current speculative momentum relies entirely on economic stability and continuous institutional inflows. Large capital allocators demand clear macroeconomic signals before committing fresh capital to this highly volatile asset class. The trajectory depends on whether the largest digital asset can maintain structural integrity above key thresholds as it navigates a highly uncertain global landscape.

Editor’s note: e27 aims to foster thought leadership by publishing views from the community. You can also share your perspective by submitting an article, video, podcast, or infographic.

The views expressed in this article are those of the author and do not necessarily reflect the official policy or position of e27.

Join us on WhatsAppInstagramFacebookX, and LinkedIn to stay connected.

The post From US$79,300 to US$82,400: Mapping the narrow corridor that decides Bitcoin’s September appeared first on e27.

Posted on Leave a comment

Why Kyoto, not Tokyo, is Japan’s real deeptech bet

Ask most investors where Japan’s startup action is, and they will say Tokyo without hesitation. But at this year’s IVS 2026, one of Japan’s largest startup gatherings, a quieter story was playing out an hour’s train ride south-west: Kyoto, a city better known for temples than transistors, has quietly built one of Asia’s more interesting deeptech ecosystems.

The numbers, at least on paper, are not huge. According to Kyoto City, the ecosystem now counts more than 650 startups, over 250 of them university spin-offs, backed by more than 20 venture capital and corporate venture capital firms. Compared to Tokyo’s startup density, that is a modest showing. But scale was never really the pitch. The pitch is patience and whether patience, finally connected to global capital, can be a competitive advantage rather than a liability.

A different game from Tokyo

Tokyo and Kyoto are not competing head-on, and the split is fairly clean. Tokyo dominates in SaaS, fintech, consumer marketplaces and fast-moving AI applications, the categories where speed and scale decide winners.

Also Read: Why Japan’s booming AI market is harder to crack than it looks

Kyoto’s strength, on the other hand, sits in semiconductors, robotics, materials science, life sciences and climate and energy technology: fields where breakthroughs take years, sometimes decades, and where a rushed timeline is often a red flag rather than a virtue.

That distinction matters because Kyoto is not trying to out-run Tokyo. Its compact geography, with most of its universities, research institutes, corporations and manufacturers sitting within walking or cycling distance of each other, makes the kind of slow-burn collaboration deeptech requires easier to sustain. Ideas can move from lab bench to funding to manufacturing without leaving the region, something few cities can claim at this scale.

The case, according to the money

Don Stalter, Managing Partner at Sunshine Lake, has watched Japan since 2011, when he worked on Groupon and Airbnb’s international expansion before becoming an early backer of Deel and Canva. His read on Kyoto is unambiguous: the city has “something money can’t buy and speed can’t replicate”, a manufacturing lineage running through Nintendo, Kyocera, Murata, Omron, Shimadzu and Horiba — companies that he says chose depth over fashion and stayed independent long enough to become irreplaceable links in global supply chains.

He points to three concrete strengths. Kyoto University’s research density, which has produced a notable share of Japan’s Nobel laureates, including the iPS cell breakthroughs behind regenerative medicine. A steady renewal of talent, with roughly one in ten Kyoto residents a student. And a cultural tolerance for long timelines that, in his view, cannot simply be bought with venture capital.

But Stalter is careful not to romanticise the gap. What Kyoto lacks, he argues, is not science or talent but bridges: early-stage global capital, global customers from day one, and networks willing to treat a Kyoto founder the same way they would treat one in San Francisco. He also flags the recycling problem common to younger ecosystems, a handful of big exits whose founders and early employees reinvest back into the next generation is still largely missing in Kyoto’s case.

The founder’s view

Hide Morita, CEO of fan-engagement platform Queri and grandson of Sony co-founder Akio Morita, offers a more grounded, on-the-ground version of the same argument. Tokyo, he says plainly, has easier access to capital, customers and large corporations. What Kansai offers instead is depth — engineering and manufacturing knowledge concentrated in one place, built by companies such as Kyocera, Murata and Nintendo that became world-class by narrowing rather than diversifying.

Morita’s own company is a useful proof point of the region’s slower logic. Queri connects Japanese and Asian entertainment companies with fans overseas, where roughly 40 per cent of its users are already based outside Japan. Building the infrastructure to serve that demand, he says, is “slow, unglamorous work”, not unlike the deeptech ventures Kyoto is known for, which depend on universities, engineers, manufacturers and investors staying aligned over years rather than product cycles.

Also Read: Japan is moving into Southeast Asia faster than the West, and most brands haven’t noticed yet

Like Stalter, Morita is sceptical that capital alone solves the harder problem. Kyoto’s more than 650 startups are not short of technology, he argues; they are short of the operating experience (sales, hiring, international expansion) needed to take a lab breakthrough global. His prescription is specific: don’t try to turn Kyoto into another Tokyo or Silicon Valley. Keep the long-term mindset and technical depth, and pair it with far better access to the rest of the world.

What’s actually being built

The specifics back up the pitch. TreGem Biopharma, a Kyoto University spin-off, is developing what it describes as the world’s first tooth-regrowth drug, an antibody therapy targeting a protein called USAG-1, with an initial focus on patients born without a full set of teeth. DeepForest Technologies uses AI to analyse drone footage and identify individual tree species and carbon absorption at single-tree resolution — a granularity increasingly demanded by carbon credit buyers and by Japan’s ageing, postwar-planted forests.

Kyoto Fusioneering has taken a “picks and shovels” approach to fusion energy, building the exhaust and fuel-cycle systems fusion plants will need rather than reactors themselves, and has reportedly become a supplier to several private fusion developers internationally. EneCoat Technologies, meanwhile, is developing perovskite solar cells that generate electricity even under cloudy skies or indoor lighting, thin and flexible enough to apply to windows rather than rooftops.

None of these are Tokyo-style growth stories. They are long-horizon bets that only make sense if the surrounding ecosystem — universities, manufacturers, patient capital — stays intact long enough to see them through.

The bet, stated plainly

Kyoto’s proposition to international founders and investors is narrow but specific: a compact city where research institutions, manufacturers, government and capital sit close enough together to move fast on slow science, a manufacturing culture with genuine present-day depth in precision engineering, and a globally recognisable brand that needs no introduction.

Also Read: Beyond market entry: Japan and Southeast Asia in a fracturing world

Whether that is enough remains an open question. Deeptech ecosystems live or die on decades, not news cycles, and Kyoto’s recycling of capital and talent is still early. But the underlying argument — that a thousand years of patience, finally wired into global capital, might outlast speed — is at least a coherent one. Tokyo built Japan’s startup scene on speed. Kyoto is testing whether the opposite instinct can work just as well.

This article was originally published by Blockbox, a media outlet that reports on the Japanese startup scene.

The post Why Kyoto, not Tokyo, is Japan’s real deeptech bet appeared first on e27.

Posted on Leave a comment

GCash operator Mynt wins SEC approval for up to US$1.63B Philippine IPO

The long-anticipated public market debut of GCash operator Mynt has moved a step closer, after the Philippine Securities and Exchange Commission approved the company’s initial public offering worth up to about US$1.63 billion.

In a statement on Friday, the SEC said its Commission En Banc had resolved to render effective Mynt’s registration statement covering up to 66.9 billion common shares, subject to the company meeting remaining regulatory requirements.

Also Read: 48 PE investors, US$3.96B deployed, and not a single IPO exit in five years. Something is broken.

The decision clears a key hurdle for what could become one of the Philippines’s largest listings in recent years, and a closely watched test of investor appetite for Southeast Asian fintech at a time when public markets remain selective about growth-stage technology companies.

Mynt, the company behind mobile wallet and financial services platform GCash, plans to offer up to 1.61 billion common shares through a primary offer. A selling shareholder will also sell up to 6.42 billion shares, while the transaction includes an overallotment option of up to 1.20 billion shares.

The shares will be priced at up to around US$0.18 each. Assuming the overallotment option is fully exercised, Mynt expects to raise net proceeds of up to about US$1.58 billion from the total offer. Of that, roughly US$264 million in net proceeds from the primary offer will be used to fund growth in digital financial services, product development, and general corporate purposes.

Based on the latest timetable submitted to the SEC, the offer period will run from October 6 to 12. Mynt is aiming to list on the Main Board of the Philippine Stock Exchange on October 20 under the ticker symbol “GCASH”.

A market bellwether for Southeast Asian fintech

For the Philippine market, the approval is significant not only because of the size of the deal, but because of what Mynt represents. GCash has become one of the country’s most recognisable consumer technology brands, riding the rapid shift from cash to mobile payments during and after the pandemic. Its app has expanded well beyond peer-to-peer transfers and bills payment into savings, credit, insurance, investments, and merchant services.

That evolution mirrors a broader Southeast Asian fintech playbook. Across the region, digital wallets started as payments tools, often subsidised heavily to win users and merchants. Over time, the strongest platforms have tried to move into higher-margin financial services, using transaction data and distribution scale to offer lending, wealth products, and insurance.

The Philippines has been one of the more fertile markets for this model. The country has a young, mobile-first population, a large base of underbanked consumers, and a fragmented geography that makes branch-heavy banking expensive. Remittances, both domestic and overseas, are also central to household finances, creating demand for low-cost digital money movement.

Also Read: When IPOs freeze, liquidity finds another way

But scale does not automatically translate into public market success. Investors will look beyond GCash’s brand recognition and user base to assess the durability of its revenue, the economics of its lending and financial services products, and the cost of maintaining growth in a competitive market. The listing will likely be read as a valuation benchmark not just for Philippine tech, but for regional fintechs that have spent years waiting for clearer IPO windows.

Lower float rule gives large issuers more room

Mynt is also the first company to benefit from the SEC’s lower public float requirement for large issuers. The regulator allowed the company to have a minimum initial public float of 12 per cent, instead of the usual 15 per cent.

A public float refers to the portion of a company’s shares that is available for public trading. Lowering the requirement for large issuers can make it easier for sizeable companies to list without forcing existing shareholders to sell a larger stake at the IPO stage. For regulators and exchanges, the trade-off is between attracting marquee listings and ensuring enough liquidity for public investors.

The Philippines, like several markets in Southeast Asia, has been trying to deepen its capital markets and persuade more high-growth domestic companies to list at home rather than look offshore. A successful GCash listing would give the Philippine Stock Exchange a rare technology anchor at a time when regional exchanges are competing to host the next generation of consumer internet, fintech, logistics, and climate-tech companies.

Singapore has long positioned itself as the region’s financial hub, while Indonesia has seen major listings from digital economy names such as Bukalapak and GoTo. The Philippines has produced fewer large public tech listings, making Mynt’s IPO especially important for local market sentiment.

What Mynt plans to do with the money

The company has said that proceeds from the primary offer will go towards digital financial services growth, product development, and general corporate purposes. That broad use of funds suggests Mynt is still investing for expansion rather than treating the IPO purely as a liquidity event.

In practical terms, product development could mean deeper work across areas such as credit scoring, fraud prevention, wealth management tools, merchant services, and embedded finance. In emerging markets, digital finance platforms often face a delicate balance: they need to widen access to financial products, but must also manage credit risk, cybersecurity, compliance, and consumer protection.

That scrutiny is likely to intensify once Mynt becomes a listed company. Public investors will expect more transparency around revenue mix, margins, bad loans if lending becomes a bigger contributor, and the regulatory risks attached to financial services. The company will also need to show that it can keep users engaged even as rivals push their own wallets, banks, and payment ecosystems.

The competitive field

GCash’s most direct domestic challenger is Maya, the fintech platform under Voyager Innovations and backed by PLDT, which has built its own wallet, payments, and digital banking ecosystem. Traditional banks in the Philippines are also accelerating their digital offerings, while card networks and payment processors remain deeply embedded in merchant transactions.

Regionally, Mynt sits in a crowded field of wallet and super-app players. Grab has built payments and financial services across several Southeast Asian markets, while Sea Group’s ShopeePay and SeaBank link commerce, payments, and banking. In Indonesia, GoTo’s GoPay and DANA compete aggressively for wallet share, while Vietnam’s MoMo remains one of the region’s best-known standalone e-wallets. Malaysia’s Touch ’n Go eWallet has also scaled through transport, retail, and financial services use cases.

The question for Mynt is whether GCash can maintain its domestic dominance while proving that its model has the margins and discipline public investors demand. Unlike regional super-apps that operate across multiple countries, Mynt’s strength is concentrated in the Philippines. That focus can be an advantage if it produces deeper local penetration, but it also limits the geographic diversification that some investors may prefer.

A listing that could set the tone

Mynt’s IPO comes at a time when Southeast Asian technology companies are being judged more soberly than during the low-interest-rate boom. Growth still matters, but profitability, governance, and capital efficiency now carry more weight. The region’s private markets have adjusted to this reality; a major public listing will show how far that reset has travelled.

Also Read: The IPO window is open, and SEA startups are walking through

For Philippine startups, the debut could be a morale boost. A strong listing would show that domestic capital markets can support large technology companies and provide an exit path for founders, employees, and early investors. A weak reception, however, would reinforce caution around tech valuations and push more late-stage companies to delay IPO plans.

Either way, GCash’s move to the public market will be watched far beyond Manila. It is not just a fintech IPO. It is a test of whether one of Southeast Asia’s most widely used digital finance platforms can translate everyday consumer behaviour into a durable public company story.

The post GCash operator Mynt wins SEC approval for up to US$1.63B Philippine IPO appeared first on e27.

Posted on Leave a comment

The US$103K visa fee is a gift to SEA’s talent pool if the region actually wants it

Every few years, Washington slams a door and Asia is told to catch the people falling out of it. It happened after the dot-com bubble. It happened after the 2020 H-1B tightening. It is happening again now, and the instinct across Southeast Asian boardrooms and government press releases will be the same: cue the victory lap.

Before anyone in Singapore, Jakarta or Ho Chi Minh City breaks out the “brain gain” slide deck, it is worth asking whether this region has ever actually won this fight, or just told itself it did.

A door slams, again

In late August, the Trump administration proposed a US$103,265 annual fee for new H-1B visas, a near-500-fold jump from the previous US$215 charge. It follows an earlier US$100,000 fee announced last September that briefly triggered chaos — with Amazon, Microsoft and JPMorgan telling H-1B staff to rush back into the US before a midnight deadline — before a US court struck it down.

Also Read: Taiwan’s startup talent problem is a matching problem, not a shortage

The back-and-forth has not calmed anyone’s nerves. Fiscal year 2027 H-1B registrations have fallen 38.5 per cent, and workers are increasingly weighing Canada, the UK and the Gulf as landing spots instead of gambling on Washington’s next move.

On workplace forum Blind, sentiment has gone from outrage to something closer to resignation, a shift TeamBlind chief executive Sunguk Moon has called a trust signal more telling than any hiring statistic.

Indian voices reacted fastest and loudest, given that Indian nationals hold roughly 70 per cent of H-1B visas. Former NITI Aayog chief executive Amitabh Kant framed it bluntly on social media as America’s loss and India’s gain, predicting the fee would push “the next wave of labs, patents, innovation and startups” toward Bangalore, Hyderabad, Pune and Gurugram. Andhra Pradesh’s IT minister has talked up the state’s role in a national “brain gain” story built on Global Capability Centres (GCCs), the in-house offshore units multinationals now use for product development and R&D rather than back-office support. India already hosts around 1,700 of them, generating an estimated US$68 billion in direct value-add, and more than 35,000 returning technologists have joined GCCs, homegrown startups or global delivery centres since 2022.

We have run this experiment before

This is not a new story, which is precisely the point. Research from economists Gaurav Khanna and Nicolas Morales on the original dot-com-era H-1B cap found that Indian engineers who were shut out of the US, or who returned home after their visas expired, helped build India’s software export industry into a global force — a genuine, measurable case of one country’s restriction becoming another’s foundation. It is the closest thing this debate has to a control group, and the finding cuts both ways: brain gain is real, but it took a generation to compound, not a single visa cycle.

Southeast Asia’s own attempt to capture skilled migration has moved at a similarly unglamorous pace. Singapore’s Overseas Networks & Expertise Pass (ONE Pass), the country’s marquee tool for luring senior global talent with no requirement to work for a single employer, has grown from roughly 3,600 holders at the end of 2023 to 8,500 by the end of 2025. Respectable growth,  except official figures show only around one in six ONE Passes issued in 2024 went to genuinely new entrants rather than people already working in Singapore switching pass types.

Also Read: SEA’s AI talent and infrastructure: Building the foundation for regional tech leadership

Compare that with Hong Kong’s rival Top Talent Pass Scheme, which had drawn more than 150,000 applications and approved over 120,000 within three years by early 2026. Singapore is not losing this race by default; it simply is not winning it by nearly the margin the press releases imply.

What would actually make this a gift

Singapore is not standing still. From January 2027, its ONE Pass will gain a dedicated AI and Tech track, alongside rising salary floors for Employment Pass and S Pass holders, a deliberate bet on quality over volume. But a work pass, however well designed, addresses only the entry point. It says nothing about what happens once someone lands: whether the ecosystem around them can actually absorb senior engineering leadership, whether compensation and equity structures compete with what a US offer once did, and whether a returning or relocating technologist finds a real career ceiling or a glass one.

That is where the H-1B shock differs from a straightforward regional windfall. The people most likely to leave the US over a six-figure visa fee are not junior developers; they are precisely the senior, experienced hires that Southeast Asian startups have always struggled hardest to attract and retain, because the region’s funding rounds, valuations and equity culture still lag Silicon Valley’s. A US$103,265 fee does not automatically convert into a queue of veteran engineers knocking on Grab’s or Sea’s door. It converts into a queue of people evaluating every plausible alternative to the US at once, with Toronto, London, Dubai and Bangalore competing for the same talent Jakarta or Manila would also like to claim.

The real test

If Southeast Asia wants this to be more than a talking point, the fix is unglamorous: close the pay gap for senior technical and research roles, make equity genuinely competitive rather than symbolic, and treat immigration policy as one lever among several rather than the whole strategy.

India’s GCC boom did not happen because Bangalore issued a nicer visa; it happened because the work itself moved there, product mandates and all. Singapore’s ONE Pass numbers will keep climbing regardless of what Washington does next, because the pass was never really about H-1B refugees in the first place.

Also Read: The outlier advantage: Why your startup needs glitch talent

The US$103,265 fee is real, and it will genuinely push some skilled workers out of America’s orbit. Whether Southeast Asia captures them, or simply watches them pass through on the way to somewhere with deeper pockets, depends on decisions the region’s founders, investors and policymakers were already supposed to be making before this latest headline gave them an excuse to feel optimistic instead.

The post The US$103K visa fee is a gift to SEA’s talent pool if the region actually wants it appeared first on e27.