Posted on — Leave a comment

Is prompt engineering real AI development, or just good documentation?

I’ve heard both answers from people I respect. One senior engineer told me prompt engineering is “writing a very long comment and hoping.” A teammate who ships LLM features for a living told me it’s the highest-leverage skill in AI development right now. After building a fair number of LLM-powered features, I think they’re both partly right, and the useful question is when each one is true.

The case for “it’s just documentation”

A good prompt looks a lot like good documentation. It states the goal, defines terms, gives examples, lists edge cases, and says what the output should look like. If you’ve ever written a clear README or onboarding doc, you already know most of the craft.

There’s also no compiler. You can’t unit test a sentence the way you test a function. The same prompt can give different results on different days, and “it works on my five examples” tells you almost nothing. If your prompt engineering is rewording until the demo looks good, then yes, that’s editing, not engineering.

The case for “it’s real AI development”

The moment you add evaluation, the picture changes. Real prompt engineering looks like this:

  • A test set of real inputs, including the ugly ones
  • A scoring method, whether human review, rules, or a model-as-judge
  • Versioned prompts, so you can see which change helped and which broke something
  • Regression checks every time the prompt or the underlying model changes
  • Decisions about where a prompt should stop and code, retrieval, or fine-tuning should start

That isn’t documentation. It’s an engineering loop that happens to use natural language as the interface. The prompt is a component with inputs, outputs, failure modes, and a maintenance cost.

Where I land

Here’s my rough test: If you can’t tell me whether your last prompt change made things better or worse, you’re doing documentation. If you can, with numbers, you’re doing development.

The word “prompt” isn’t what separates the two. Measurement is. A prompt without evals is a guess with good grammar. A prompt with evals, versioning, and clear ownership is a real part of your system.

Also Read: To become better at prompt engineering, learn how to think like a manager

What I’d tell a team starting out

  • Write the prompt like a spec first. Clarity is half the work.
  • Build 20-50 real test cases before you tune anything. Otherwise you’re optimising for your own taste.
  • Track every prompt change like a code change. If it’s not in version control, it doesn’t exist.
  • Know when to stop prompting. Some problems need retrieval, tools, or plain old code, not another paragraph of instructions.
  • Re-run your tests when the model updates. Prompts are tied to the model they were written for.

The uncomfortable part

If prompt engineering is “real” development, then a lot of AI projects have been shipping without anyone doing development. They have impressive demos and no tests.

If it’s “just documentation,” then the people getting reliable results are doing something else on top of it that we haven’t named yet. I suspect that’s the answer: the prompt is the visible tip, and the engineering is the eval and iteration process underneath.

Your turn

Where do you draw the line? Have you shipped a prompt-heavy feature to production, and what was the thing that actually made it reliable? I’d especially like to hear from people who think I’m wrong.

—

Editor’s note: e27 aims to foster thought leadership by publishing views from the community. You can also share your perspective by submitting an article, video, podcast, or infographic.

The views expressed in this article are those of the author and do not necessarily reflect the official policy or position of e27.

Join us on WhatsApp, Instagram, Facebook, X, and LinkedIn to stay connected.

The post Is prompt engineering real AI development, or just good documentation? appeared first on e27.

Posted on — Leave a comment

The hidden economics of returns in Southeast Asian e-commerce

A customer orders a product online, receives it and requests a refund. From the buyer’s perspective, the process may involve a few taps and a parcel handed to a courier. For the merchant, it can initiate a second supply chain involving transportation, inspection, reimbursement, inventory recovery and additional administrative work.

This matters in Southeast Asia, where e-commerce gross merchandise value is projected to reach US$226 billion in 2026, according to the latest Google, Temasek and Bain e-Conomy SEA report. While marketplaces compete to make purchasing easier, retailers must also manage the economics of transactions that do not become completed sales.

Returns are therefore more than a customer-service expense. They represent a commercial commitment whose actual cost depends on product margins, logistics infrastructure, payment arrangements and the ability to recover inventory value.

The refund is only the visible part of the financial loss

A conventional order-level profitability calculation subtracts product costs, marketplace commissions, payment fees, fulfilment expenses and customer acquisition costs from retained revenue. Once an order is returned, however, several additional expenses enter the calculation.

The original shipment may already have consumed transportation and packaging resources. The merchant may then incur collection charges, inspection costs, repackaging expenses and customer-service work. Depending on marketplace rules and contractual arrangements, some commissions and payment fees may be reversed while others remain payable. The financial burden can also be distributed differently between the merchant, platform and logistics provider.

Consider a hypothetical retailer earning US$5 in contribution margin on a successfully completed order but losing US$9 when an order is returned, after accounting for recoverable inventory value and processing costs. At a 10 per cent return rate, expected contribution is US$3.60 per order. At 25 per cent, it falls to US$1.50. These figures are illustrative rather than regional estimates, but they demonstrate how return frequency affects profitability.

The important measurement is expected contribution across retained and returned transactions. Refunds should not be counted twice by treating reversed sales revenue and the refund itself as separate losses. Equally, recovered inventory should not automatically be valued as though it were ready for immediate resale.

Also Read: The invisible shopper rewriting Asia’s e-commerce playbook 

Southeast Asia does not operate through one logistics model

The economic consequences of a return vary substantially across regional markets. Recovering a parcel within Singapore’s dense urban environment is different from collecting one across Indonesia’s islands or from a remote Philippine location. Transportation distances, carrier networks, consolidation capacity and warehouse accessibility influence the cost of moving goods backward.

Payment arrangements introduce another distinction. Cash-on-delivery transactions can generate failed deliveries when customers refuse parcels before payment, leaving the operator with transportation costs but no completed sale. These incidents differ from returns initiated after receiving and paying for merchandise. Although cash on delivery is declining across Southeast Asia, its continued relevance differs between countries, making a single regional assumption inappropriate.

Cross-border commerce creates additional complexity. An inexpensive product may be profitable to ship internationally through consolidated outbound deliveries but uneconomical to return individually. Depending on product value, contractual conditions and applicable consumer protections, a merchant might choose local resale, liquidation, replacement or a refund without physical recovery.

The cheapest logistical option is not necessarily the most profitable. A retailer must compare transportation costs with recoverable product value, inventory availability and the operational consequences of each alternative. Reverse logistics should consequently be designed around product characteristics and destination markets rather than treated as a simple reversal of outbound delivery.

Recovering the product does not mean recovering its value

Returned merchandise must be inspected before its economic value can be determined. An unopened product may qualify for immediate resale, while another requires repackaging, refurbishment or a substantial discount. Some products cannot be sold again under their original commercial conditions.

These differences become particularly important across categories. Apparel may require condition checks and repackaging. Consumer electronics can involve functionality testing, warranty assessment and potential depreciation. Damaged or hygiene-sensitive products may retain little recoverable value despite the cost of transporting them back.

Time also affects profitability. Merchandise undergoing collection and inspection remains unavailable for sale, potentially creating inventory shortages even when returned stock physically exists elsewhere in the network. Seasonal products and rapidly depreciating items may lose value while operators decide how to process them. Refunds can additionally create a working-capital gap before any resale proceeds are received.

An effective recovery decision therefore compares the net proceeds available through different channels. Returning an inexpensive item to a central warehouse may cost more than selling it through a local liquidation partner. Refund-without-return arrangements can sometimes reduce expenses, but poorly controlled policies also introduce fraud risks, inventory discrepancies and avoidable waste.

The objective is not to recover every parcel. It is to determine which recovery process preserves the greatest economic value after all associated costs.

Also Read: Profitable e-commerce: Making real money in the new year

Return policies influence conversion as well as profitability

Restricting returns may appear attractive when reverse-logistics expenses rise. However, a return policy also influences purchasing behaviour. Customers buying unfamiliar products cannot physically examine them before payment, making the possibility of a refund part of the perceived security of the transaction.

Research published in the American Economic Journal: Microeconomics in 2024 examines this tension between the costs generated by returns and the efficiency gained when consumers can evaluate products after purchase. From a retailer’s perspective, a generous policy can therefore produce benefits through greater willingness to buy, even while increasing operational expenses.

The commercial calculation must account for both effects. Reducing return eligibility could lower processing costs while discouraging customers whose purchases depend on reassurance. Conversely, making every return exceptionally convenient may increase conversion without generating sufficient additional contribution to cover the resulting expenses.

Preventing avoidable returns can be more effective than introducing blanket restrictions. Accurate sizing information, realistic product images, technical compatibility details and stronger seller-quality controls address causes of dissatisfaction before an order is placed. Policies should distinguish legitimate product defects from preference-based returns while respecting consumer rights and marketplace obligations.

The question is not simply whether returns should be free. It is whether the purchasing confidence generated by a particular policy creates enough additional economic value to justify its complete cost.

Profitability must be measured after the reverse journey

Managing these economics requires connecting information that frequently sits in separate operational systems. Order records identify the original sale, payment systems record settlements, logistics providers track movements, and warehouse systems establish whether returned merchandise can be resold.

Retailers need a consistent view of these events. Return rates should distinguish items returned after delivery from failed deliveries and cancellations, with clearly defined denominators. Recovery value, time to refund, processing expenses and contribution margin should be analysed by product category, sales channel, carrier and destination.

This creates a more useful basis for evaluating marketplace relationships. The organisation deciding how attractive a return policy should appear is not necessarily the organisation financing its execution. Shipping subsidies, seller-liability rules and reimbursement arrangements can create different economic incentives across the same transaction.

For sellers, understanding this allocation is essential when deciding whether a channel remains profitable. For marketplaces, it helps identify situations where additional purchasing convenience generates costs elsewhere in the network.

The underlying challenge is not to make returns difficult for customers or to eliminate them indiscriminately. It is to build a system capable of providing reliable remedies while recovering inventory value efficiently and maintaining sustainable margins.

Southeast Asian e-commerce has developed increasingly sophisticated capabilities for attracting customers and delivering products. Its next profitability challenge also lies in understanding what happens when those products travel in the opposite direction. Growth measured through merchandise value tells only part of the story. The economic result emerges after the entire transaction, including the possibility of its reversal, has been accounted for.

—

Editor’s note: e27 aims to foster thought leadership by publishing views from the community. You can also share your perspective by submitting an article, video, podcast, or infographic.

The views expressed in this article are those of the author and do not necessarily reflect the official policy or position of e27.

Join us on WhatsApp, Instagram, Facebook, X, and LinkedIn to stay connected.

The post The hidden economics of returns in Southeast Asian e-commerce appeared first on e27.

Posted on — Leave a comment

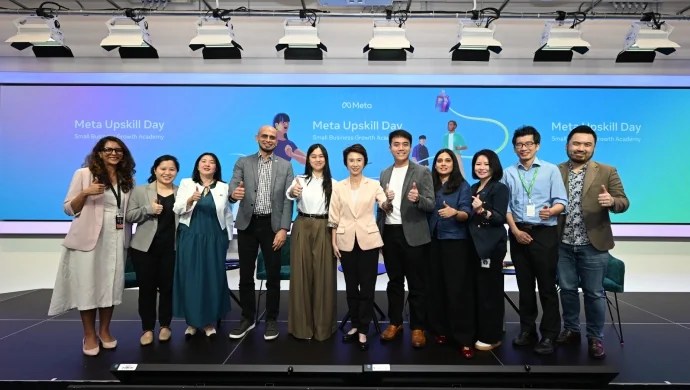
Meta wants to teach Singapore’s small businesses AI. It also wants them on WhatsApp

SpeakEasy Lab is a two-person communication training business in Singapore, which means that when both founders are teaching, nobody is answering customers. Nobody human, at least. Routine enquiries that once waited an hour or more now get near-instant replies from Meta Business Agent, an AI agent running on WhatsApp and Messenger. The founders reckon it saves them 10 to 15 working hours a week.

That anecdote took centre stage at Meta Upskill Day 2026, where the social media giant gathered more than 180 small businesses, heartland merchants and creator-entrepreneurs in Singapore for hands-on training on its AI tools. Senior Minister of State Low Yen Ling attended as Guest of Honour. The event forms part of Meta’s Small Business Growth Academy.

Also Read: Malaysian SMEs grapple with a growing “confidence gap” in AI adoption

Meta’s pitch is that Singapore’s small firms want to use AI but do not know how. The more interesting question is whose AI they end up learning.

A Meta survey finds small businesses need Meta’s help

The case rests on new YouGov research commissioned by Meta. It found that 94 per cent of Singapore small business owners surveyed agree small businesses need more guidance to get the full benefit of AI. Among those whose businesses have used AI, 82 per cent report a positive productivity impact over the past 12 months, and 62 per cent of that group say they spend the time saved improving existing work.

The numbers deserve a pinch of salt. YouGov polled 3,983 owners across nine markets, from Australia to Japan, between 6 August and 2 September 2026, without disclosing how many were in Singapore. Its own methodology note says the findings are not nationally representative, and that differences between markets may partly reflect translation and local response habits. A platform commissioning research that concludes small businesses need guidance, then supplying the guidance, is less a conflict of interest than a business model.

Still, the direction matches what e27 has heard elsewhere. Singapore SMEs are buying back time with AI, but messy data keeps many pilots stuck, and across the region, SMEs adopt AI four times slower than big business.

The chatbot is the easy part

Customer engagement is where Meta sees its clearest opening. Some 52 per cent of Singapore owners surveyed have used, or would be interested in using, AI-powered customer responses. The Business Agent masterclass walked participants through setting up agents to handle enquiries on WhatsApp and Messenger, with Meta’s business messaging specialists on hand.

For a micro-business that lives on chat messages, that is genuinely useful. But answering the question is rarely where the work ends. Bookings, invoices, refunds and stock checks still have to happen, and what an SME really needs is the work after the chat done. An agent that cannot reach a merchant’s calendar or inventory simply moves the bottleneck down the line.

Also Read: Meta, Singapore Police disrupt 3.7M scam-linked assets across Facebook and Instagram

There is a governance question too. Staff are already bringing their own AI to work, and an agent speaking for a business on WhatsApp becomes a liability the moment it quotes the wrong price or invents a refund policy. Meta’s announcement says little about how merchants should check what their agents tell customers.

Dream Render walks into a crowded edit suite

Meta also used the event to introduce Dream Render, a browser-based tool that turns a short product description or photo into a draft product video in minutes. Users can adjust shots, framing, pacing, voiceover and on-screen text before approving the final cut, which they download and publish themselves with a label showing it was made with AI. Sign-in runs through an existing Facebook page or Instagram professional account.

The demand is there: 46 per cent of owners surveyed said AI training for marketing and content creation would be useful. Haldy, a Singaporean maker of sugar-free turmeric mints, credits the tool with quickly building its social media presence.

Meta is hardly first to this, though. ByteDance’s CapCut and Canva already put AI video generation in front of the same merchants, and Google, Microsoft and TikTok run their own skilling drives for Singapore’s small businesses. Meta’s edge is distribution: the video gets made next to where the ad will run. The recent appointment of Dhruv Vohra to lead its Southeast Asia business, framed around AI and chat commerce, and the arrival of Meta’s Muse in Singaporesuggest a wider AI stack is being built around exactly these users.

Training, or onboarding?

Since launching in Singapore in 2021, Upskill with Meta says it has trained more than 500 small businesses and upskilled over 4,500 entrepreneurs, working with Digital Industry Singapore, AI Singapore, Enterprise Singapore and the Economic Development Board. This year’s edition also plugs into EnterpriseSG’s partnership with the Heartland Enterprise Centre Singapore, whose business advisers are being equipped to pass AI tools on to neighbourhood merchants.

The fit with the National AI Strategy and the National AI Impact Programme is real, and practical training beats another glossy keynote. But 500 businesses in five years is a rounding error against Singapore’s roughly 300,000 SMEs, and the curriculum is built entirely on Meta’s own products.

Also Read: AI-powered business automation: How SMEs are transforming operations in Southeast Asia

For a heartland merchant, free training that saves 10 hours a week is a good deal. The catch is that skills learnt inside one platform’s tools tend to keep a business on that platform, which is worth weighing alongside subsidies such as the EDGE Grant that let SMEs shop around for software. Meta is not wrong that small businesses need guidance on AI. It just happens to be the one selling the map.

The post Meta wants to teach Singapore’s small businesses AI. It also wants them on WhatsApp appeared first on e27.

Posted on — Leave a comment

AI is changing how we learn, work and invest. Venture capital must change too

I recently started one of my lectures at Nanyang Technological University (NTU) in Singapore by asking students to think about how education has changed over the past 30 years.

When I was studying engineering at university, there was no internet. Information was difficult to access. We spent hours in libraries, reading textbooks, taking notes and memorising facts. Having knowledge was valuable because finding information required considerable effort.

Years later, when I did my MBA, the internet had changed everything. Information was suddenly available to almost everyone. We no longer needed to spend so much time looking for facts. The real challenge was understanding that information, interpreting it and applying it to business problems.

Today, we are entering a third stage. With AI, students can access information and analysis, explanations and proposed solutions. They can ask AI to develop a business plan, analyse a company, build a financial model or explain a complex technology. Tasks that previously took days can now be completed in minutes.

I believe education must focus much more on understanding principles, learning methods and developing judgement. Students still need to understand how businesses operate, how scientific discoveries become commercial products, how financial models work and why some companies succeed while others fail. Memorising large amounts of information is becoming less important.

The challenge is learning how to ask the right questions, challenge the answers and apply knowledge to real situations. This is why experience becomes particularly valuable. In my VC lectures, I use real investment cases, including successful investments and companies that ultimately failed. Students can ask AI to analyse these companies, but understanding why investors made certain decisions, what information was available at the time and what went wrong is a different matter. Learning from people who have actually made these decisions, including mistakes, is becoming an increasingly important part of education.

AI is turning venture capital upside down

I see a similar transformation happening in venture capital, where I have spent over 10 years. Traditionally, when a VC firm received a pitch deck, a junior analyst would review the startup, research the market, examine competitors, check financial assumptions and prepare an initial investment assessment.

Today, one of the first things many investors do is to upload a pitch deck to an AI tool and ask it to identify strengths, weaknesses, inconsistencies and potential red flags. AI can review a company’s business model, challenge its market assumptions, compare competitors and identify gaps in its financial projections within minutes. I use AI for this type of initial analysis. It is particularly useful for identifying questions that deserve further investigation.

Also Read: Singapore is paying startups to secure the AI agents it is racing to deploy

There are some limitations. AI can identify that a company’s revenue assumptions look aggressive. It cannot reliably tell whether the founder has the ability to deliver them. It can compare technologies, but cannot assess the quality of a management team or the strength of relationships with customers. It could also be wrong, especially when information is incomplete or when analysing technologies that are still being developed, which is exactly the case for most of the tech startups.

This is why I see AI as a good assistant and not as a decision maker. The implications for VC firms are important. Traditionally, investment teams have operated like pyramids, with many junior analysts doing research and a smaller number of senior professionals making investment decisions.

AI is turning this pyramid upside down. Firms may need far fewer junior analysts performing routine research, while relying more heavily on experienced investors who can interpret findings, challenge assumptions, build relationships and make decisions. In other words, AI reduces the cost of analysis but increases the relative value of judgement.

Making money from AI is harder than using it

AI is creating enormous investment opportunities, and also creating challenges for VC investors. Almost every startup today claims to use AI. Many are building applications around existing LLMs, adding industry-specific features or improving workflows. Some of these businesses will become successful, but many face a fundamental problem: their technology is relatively easy to replace.

If a company builds a product around an existing AI model, nothing prevents another company from building something similar or the model provider from introducing the same functionality directly. This makes it difficult to identify which companies can build lasting competitive advantages. I believe some of the most attractive opportunities are in solving the bottlenecks that limit AI development and adoption.

Also Read: Open code, unowned risk: The governance gap in business-critical email

One example is Positron AI, a company developing specialised hardware for AI inference. As AI applications expand, the cost of running models becomes increasingly important. The industry needs more computing capacity, better energy efficiency and lower costs. Positron is addressing these challenges through hardware designed specifically for AI inference workloads.

Its rapid increase in valuation illustrates investor demand for technologies addressing fundamental AI infrastructure problems. Positron raised capital at a valuation of approximately US$1 billion in February 2026, followed by a September financing round at a valuation of US$5 billion, a fivefold increase in seven months.

It is not alone. In July, fellow inference chipmaker Etched raised US$300 million at a US$10.3 billion valuation, while SambaNova raised US$1 billion at a US$11 billion valuation. Of course, a rising valuation does not guarantee investment returns. The company still needs to execute, compete and deliver commercial results.

These examples highlight an important distinction between building another AI application and developing technology that addresses a major constraint on the industry’s growth. For venture capital investors, understanding this distinction is critical. The biggest opportunities may not come from companies that simply use AI, but from those making AI faster, cheaper, more efficient and more widely available.

The next generation of venture capital

I believe that AI is here to stay, and its impact will be much greater than simply improving productivity. It is changing what students need to learn, how professionals work and where investors should look for opportunities. For universities, the priority should increasingly be teaching principles, practical methods and critical thinking supported by real-world experience. For VC firms, AI will make research and initial analysis faster and cheaper.

Successful investing will depend on understanding technology, recognising exceptional founders and making difficult decisions under uncertainty. As for investors looking to benefit from the AI revolution, the challenge is separating companies with sustainable competitive advantages from those simply adding AI to existing products.

AI will not make everyone a successful investor, just as the internet did not make everyone a successful entrepreneur. Those who learn to use AI efficiently, while developing the experience and judgement to challenge its conclusions, will have a significant advantage. Venture capital spent years investing in companies that disrupt traditional industries.

Now it is time for VC firms to rethink their own business models.

—

Editor’s note: e27 aims to foster thought leadership by publishing views from the community. You can also share your perspective by submitting an article, video, podcast, or infographic.

The views expressed in this article are those of the author and do not necessarily reflect the official policy or position of e27.

Join us on WhatsApp, Instagram, Facebook, X, and LinkedIn to stay connected.

The post AI is changing how we learn, work and invest. Venture capital must change too appeared first on e27.

Posted on — Leave a comment

Beyond the chatbot: How AI is reshaping customer service in Southeast Asia

A football fan in Bangkok wants to know which streaming package carries tonight’s match. Kick-off is approaching, and the answer is buried somewhere on the provider’s website.

For the customer, a delayed response is frustrating. For the streaming company, it could mean a missed subscription.

Multiply that interaction by thousands of customers, several languages and a growing number of communication channels, and the appeal of AI-powered customer service becomes clear.

Across Southeast Asia, businesses are introducing AI into their support operations. The technology is beginning to handle work previously reserved for employees, from retrieving account information to guiding customers through transactions.

The problem with fragmented communication

Customer service in Southeast Asia has its own complications. LINE is widely used in Thailand, WhatsApp in Indonesia and Malaysia, and Zalo in Vietnam. Businesses must also contend with email, telephone calls and social media messages.

For companies operating across several markets, managing these channels can be cumbersome. Customer information is scattered across systems, conversations lose context and employees spend time piecing together what happened during previous interactions.

Customers frequently end up repeating themselves.

According to Ipsos’ 2026 customer experience research in Thailand, only 35 per cent of customer issues were fully resolved. The study also found that 70 per cent of consumers felt they shared roughly equal responsibility with brands for the effort involved in resolving problems.

These findings suggest that digitalisation has yet to deliver the simplicity customers expect.

Also Read: Is prompt engineering real AI development, or just good documentation?

What AI can do differently

Traditional chatbots were built around predefined responses. They could answer common questions, direct customers to relevant information and escalate more complicated requests.

Recent advances in AI have expanded what can be automated.

When connected to a company’s internal systems, AI agents can retrieve account details, arrange appointments, initiate requests and assist with transactions. Their usefulness increasingly depends on what they can accomplish rather than how convincingly they can hold a conversation.

Customer expectations appear to be changing accordingly.

A July 2026 Gartner survey of 3,566 customers found that 58 per cent of those using generative AI had used it to complete a task. Among business customers, the figure reached 74 per cent.

The potential extends beyond answering enquiries. A customer asking about a delayed delivery may want the problem resolved. Someone checking the availability of a streaming package may be ready to purchase it.

In both cases, the quality of service depends on what happens after the initial response.

One example from Thailand

Thailand’s streaming service TrueVisions NOW provides an example of how this technology is being put to work.

The company has deployed an AI customer service agent built on klink.cloud, a platform that brings telephone, email, WhatsApp, LINE and other communication channels into a shared environment.

In an August 2026 case study, Klink describes how TrueVisions NOW introduced the agent to answer questions about sporting events, programme availability and subscription packages in Thai and English.

According to Klink, the proportion of enquiries resolved by AI rose from 50 per cent in the first week to 67 per cent by the fourth. Median reply times fell to approximately five seconds, while abandoned conversations decreased by more than half. These are the vendor’s own figures, and they measure speed rather than whether problems stayed solved.

Beyond those efficiency gains, the deployment highlights an interesting commercial opportunity.

A subscriber asking whether a particular football match is available might simply need information. Another may be comparing subscription packages before purchasing. A third could be having trouble accessing content already paid for.

Recognising these different intentions allows the system to respond accordingly. The agent can also recommend subscription packages based on the content customers are looking for, bringing product discovery and sales into the customer service conversation.

For subscription-based businesses, particularly those experiencing sudden peaks in demand around live events, this combination of immediate assistance and relevant recommendations offers practical advantages.

It also suggests that the traditional boundaries between customer support, sales and operations are becoming less distinct.

Also Read: What’s actually changing for Asia Pacific businesses in the age of AI

Automation has its limits

The commercial case for AI customer service is still developing.

Reducing response times and increasing the number of automated conversations can improve operating efficiency. Yet businesses must also consider whether customers are receiving better service.

Financial returns across the industry remain uneven. Gartner reported in July 2026 that only 24 per cent of surveyed service and support leaders had demonstrated positive financial returns across their AI use cases.

Customer confidence presents another challenge. In a separate August 2026 Gartner survey, 87 per cent of respondents said access to a human agent was essential when businesses used generative AI for customer service.

There are practical reasons for that preference. AI systems can misunderstand requests, provide inaccurate information or struggle with unusual circumstances. Giving them access to customer records and transaction systems also introduces privacy and security considerations.

Businesses must decide which requests can be handled automatically, which require human approval and how customers can reach an employee when something goes wrong.

The numbers that matter

For startups operating in Southeast Asia, AI offers a way to provide multilingual support across several channels without hiring employees in direct proportion to customer growth.

The economics are attractive, particularly for businesses serving customers outside conventional office hours or dealing with unpredictable peaks in demand.

But the percentage of enquiries handled by AI tells only part of the story.

Companies also need to examine how often problems are resolved on the first attempt, whether customers return with the same issue, how much effort a transaction requires and whether service improvements affect retention or revenue.

For businesses considering similar deployments, the sensible starting point is to identify where customers encounter the most friction and determine whether AI can remove it reliably.

A five-second answer is impressive. A problem that stays solved is worth considerably more.

—

Editor’s note: e27 aims to foster thought leadership by publishing views from the community. You can also share your perspective by submitting an article, video, podcast, or infographic.

The views expressed in this article are those of the author and do not necessarily reflect the official policy or position of e27.

Join us on WhatsApp, Instagram, Facebook, X, and LinkedIn to stay connected.

The post Beyond the chatbot: How AI is reshaping customer service in Southeast Asia appeared first on e27.

Posted on — Leave a comment

Is short covering the only reason Bitcoin moved higher?

Bitcoin gained 0.73 per cent to US$73,937.65 in 24 hours, and Ethereum gained 0.519 per cent to US$2,053.91. The total crypto market rose 0.45 per cent. I read this move as a modest relief bounce after selling eased, not the start of a confirmed new trend. The figures support that view. Both assets moved with the wider market. Neither note shows a distinct asset-specific catalyst. Trading participation fell for both.

For Bitcoin, the main story is that selling pressure eased after hotter-than-expected US inflation data pushed BTC lower on November 10. News coverage linked the November 11 rise to that easing pressure. Short liquidations suggest some traders had to close bearish positions, and that forced buying likely added to the move. Traders who had bet on further declines helped lift prices when they closed those bets. That kind of buying fades once the squeeze ends.

It does not signal that long-term investors have turned more positive. This is not the same as a new bullish driver. It is a partial recovery after a selloff. Bitcoin trading volume fell 14.3 per cent over 24 hours. That drop weakens the case for a durable move. A price gain on lighter participation can reflect reduced selling rather than strong new demand. Bitcoin’s seven-day change remained down 8.06 per cent. The daily uptick therefore sits inside a weaker short-term backdrop.

The ETF flow data adds another caution. US spot Bitcoin ETFs recorded US$95 million in net outflows on November 10. Outflows remove a source of demand. They do not create fresh buying. One linked headline notes that ETF outflows hit a fourth day. I would treat that as a headwind, not a side detail. Bitcoin can rise while ETFs lose assets, but that combination makes the move less trustworthy.

A fourth day of withdrawals points to persistent caution among ETF investors. That flow can weigh on spot prices when it continues. The market can absorb one day of outflows. A run of withdrawals sends a different message about demand. My view is that the market needs more than short covering and eased selling to call this a reversal. It needs stronger participation and steadier demand.

Also Read: CPI at 0.4% broke Bitcoin’s US$73,000 floor. What happens if the Fed goes bigger?

The technical picture gives a clear map. Bitcoin trades near US$73,938. Its seven-day average is about US$74,990. Its 200-day average is about US$73,118. The recent swing low is US$72,689. If Bitcoin holds above that low and retakes US$75,000 to US$76,000, the recovery could extend. If it breaks below US$72,689, the market risks a move toward US$70,000.

I find the first condition more important than the daily gain. Holding the low would show buyers are still defending the recent range. Reclaiming US$75,000 to US$76,000 would show more than a brief rise. It would show that Bitcoin can overcome nearby resistance. Losing US$72,689 would strengthen the downside case and make the current gain look like a brief pause.

Ethereum shows a similar but weaker picture. Ethereum gained 0.519 per cent to US$2,053.91. The note describes the move as broad-market beta. Ethereum moved in the same direction as Bitcoin and the wider crypto market. It did not show a distinct Ethereum-specific catalyst.

Ethereum’s 24-hour volume fell 33.19 per cent. That is a large drop, and it limits confirmation. The Fear reading of 27 reflects cautious sentiment, but it does not explain the price move. Ethereum is down 15.03 per cent over seven days. That weak weekly performance tempers the daily gain.

Also Read: Bitcoin is bruised, not broken: Why the crypto sector is holding its ground

The Ethereum levels matter in the same way. If Ethereum holds the US$2,005 to US$2,040 support area, it could retest US$2,119. A sustained break below US$2,005 could expose US$1,900. My view is that Ethereum’s small gain is more about the wider market than about Ethereum-specific demand. That makes it vulnerable if wider-market buying fades. A support hold would keep a recovery possible.

A support break would shift attention to US$1,900. The note calls the short-term picture neutral, and I agree. That neutral label fits the data. ETH has a nearby ceiling and a nearby floor. The distance between them is modest. A trader should wait for a break before treating either direction as a real signal. The weekly decline and lower participation keep the signal weak.

The macro calendar gives the next scheduled test. US producer price data arrives on Friday, November 13 at 8:30 a.m. ET. Bitcoin’s note flags that data as the next macro trigger. I wouldn’t overstate one report, but it can shape near-term risk appetite.

The recent CPI-driven selloff shows how macro data can move crypto prices. A softer producer price reading could help the rise. A hotter reading could revive selling pressure. The market should watch how Bitcoin and Ethereum react around their key levels after that data, not just the direction of the first move.

My overall point of view is cautious. Bitcoin’s 0.73 per cent gain and Ethereum’s 0.519 per cent gain look consistent with a broader market bounce after the CPI-driven selloff. Short covering likely amplified the move.

Lower participation and ETF outflows argue against treating it as a confirmed trend reversal. Bitcoin faces resistance at US$75,000 to US$76,000 and support at US$72,689. Ethereum faces resistance at US$2,119 and support at US$2,005 to US$2,040.

The key watch is whether Bitcoin can hold US$72,689 and reclaim US$75,000 to US$76,000 after the November 13 producer price data. Ethereum needs to hold US$2,005 for its own recovery to stay alive. Until participation improves and ETF flows stabilise, I would not make any serious moves.

—

Editor’s note: e27 aims to foster thought leadership by publishing views from the community. You can also share your perspective by submitting an article, video, podcast, or infographic.

The views expressed in this article are those of the author and do not necessarily reflect the official policy or position of e27.

Join us on WhatsApp, Instagram, Facebook, X, and LinkedIn to stay connected.

The post Is short covering the only reason Bitcoin moved higher? appeared first on e27.

Posted on — Leave a comment

Jensen Huang quits Nvidia, and Southeast Asia’s chip hubs inherit the fallout

For 33 years, Nvidia had one face, one voice and one leather jacket. On Thursday, it lost all three.

Jensen Huang, who co-founded the chipmaker in 1993 and built it into one of the world’s most valuable companies, has resigned as president and CEO. According to a regulatory filing, Nvidia’s board accepted his resignation on Wednesday.

That came days after he admitted to a romantic affair with Alice Huang (no relation), a Chinese businesswoman whom US intelligence reportedly believes was working for China’s Ministry of State Security. A separate report in The New York Times alleged a second affair, this one with an Nvidia executive who reported to him.

Chief Financial Officer Colette Kress becomes interim CEO and keeps her finance role. The board also named Harvey Jones, a director since 1993 and former Synopsys chief, as Nvidia’s first-ever chair. The market had already reacted. Shares fell more than 11 per cent in premarket trading on Thursday, and the company has lost over US$300 billion in market value since last Friday.

Also Read: The Nvidia clampdown is a warning for Southeast Asia’s AI boom

None of the espionage allegations has been tested in court, and neither Huang nor Nvidia has been charged with anything. Still, the scandal’s centre of gravity sits more than 13,000 km from Santa Clara, in Singapore.

Singapore breaks its silence, and points at Washington

Alice Huang was a top executive at Megaspeed International, a Singapore-based cloud firm that grew into Nvidia’s largest buyer in Southeast Asia. CBS News reports that Megaspeed and its Malaysian affiliate, Speedmatrix, bought about US$4.8 billion of Nvidia equipment over three years.

On Thursday, Singapore’s Ministry of Home Affairs (MHA) gave its fullest account yet. Police had investigated Alice Huang, then Megaspeed’s CEO, chair and one of its key controllers, over possible offences. These included buying servers that were exported via Singapore to Malaysia without ever entering the local market. Police gave her a stern warning for knowingly providing inaccurate information to downplay her role, and she has been barred from re-entering Singapore since February. Investigations into Megaspeed and six other individuals continue.

The ministry was careful on two points. First, the spying allegation is not part of its probe. Two weeks ago, MHA denied investigating her over ties to Chinese intelligence or to Jensen Huang. Second, Singapore does not enforce other countries’ unilateral export controls, although it expects companies based there to take such rules into account.

Then came the sharper line. Singapore had sought information from Supermicro, the San Jose server maker and close Nvidia partner, and received only limited cooperation. The ministry says it raised the matter with US authorities in July 2025 and has since repeated the request to the Department of Justice and the FBI, with little to show for it. The message was clear: Singapore wants it on record that it has not been the weak link.

The Bangkok thread and a widening dragnet

Supermicro knows this terrain. In March, US prosecutors charged its co-founder Yih-Shyan “Wally” Liaw and two others with routing roughly US$2.5 billion of servers packed with Nvidia H200 and B200 GPUs to China through a Southeast Asian front company. Bloomberg later identified that company as OBON, a Bangkok-based AI infrastructure firm that has not been charged. Liaw has pleaded not guilty, and Supermicro says it was a victim of the scheme.

According to Bloomberg, the Department of Justice is now running several probes involving Nvidia, including ones focused on Megaspeed and Supermicro. Separately, Manhattan prosecutors are examining whether entities linked to Alice Huang helped move Supermicro hardware into China. Megaspeed denies wrongdoing and says inspections by US, Malaysian and Nvidia teams found no violations.

Also Read: Southeast Asia in the 2026-2030 world order: Trade, chips, AI, and capital

For a region that has spent two years pitching itself as the neutral ground of the AI race, the map is awkward. The story features Singapore as the billing address, Johor as the data hall, and Bangkok, the capital of a country chasing a US$80 billion semiconductor push, as the base of an alleged front. That puts three ASEAN nodes in one scandal, and Washington is paying attention.

Why a Santa Clara boardroom matters in Johor

Huang was more than a CEO. He was the industry’s loudest critic of export controls, which he once called “a failure”. He leaves just as Democrats prepare to take control of Congress in January. Senator Elizabeth Warren is likely to chair the Senate Banking Committee, with subpoena power, and House lawmakers have already requested a closed-door session with Huang on 18 November.

The likely result is tighter rules, and Southeast Asia sits in the blast radius. Malaysia has already introduced permits for Nvidia chip exports under US pressure, even as its exporters sell more chips without winning more of the market. Expect more end-user vetting, allocation caps and on-site audits as Washington targets the region’s chip-smuggling problem. Honest data-centre operators and GPU cloud startups will pay much of the compliance bill, and the costs will ripple across Southeast Asia’s chip supply chain.

Singapore’s own Nvidia bets, such as Singtel’s partnership with the SIT-NVIDIA centre, will not unwind over this. But the premium on trust has just gone up.

Rivals smell an opening, but CUDA is still a moat

AMD, Broadcom’s custom-silicon business and Google’s TPUs have all chipped away at Nvidia’s dominance. In China, Huawei’s Ascend chips are Beijing’s preferred substitute. A leadership vacuum invites all of them to push harder with hyperscalers that are already hedging. Yet Nvidia’s real lock-in is CUDA, its software ecosystem, and no interim CEO can lose that in a quarter. The more immediate test comes on 17 November, when Kress presents third-quarter results without the showman beside her.

Kress is familiar with that stage. She joined Nvidia in 2013 from Cisco, after stints at Microsoft and Texas Instruments, and has fronted earnings calls for more than a decade. What she lacks is founder authority, the kind that let Huang sketch the future from a stadium stage and have markets believe him.

A governance lesson Southeast Asian founders should not ignore

The quieter headline is that the world’s most consequential chipmaker appointed a board chair only after its founder left in scandal. An outside investigation, led by former acting SDNY US Attorney Joon Kim and the law firm Wachtell, Lipton, Rosen & Katz, will now examine what the company knew and when.

Also Read: Chips, corruption, and credibility: Malaysia’s semiconductor gamble faces a trust test

Many of the region’s most celebrated tech companies remain founder-led, often with the founder also holding the chair. Their boards might ask a blunt question: if their founder became the story, who would have the standing to act, and how quickly?

Nvidia will survive Jensen Huang’s exit. Whether Southeast Asia keeps its standing as the trusted middle ground of the AI race, as the investigations he leaves behind unfold, is a far more open question.

The post Jensen Huang quits Nvidia, and Southeast Asia’s chip hubs inherit the fallout appeared first on e27.

Posted on — Leave a comment

The ghost in the middle: How one manager upskilled himself out of the room

The grey ring of condensation on the laminate table had almost dried by the time he finished explaining his pipeline.

Outside the glass wall of the coffee shop at the edge of the financial district, the midday rush was beginning to churn: young associates balancing takeaway salads, delivery riders cutting across intersections, the persistent equatorial heat beating down on the pavement. Inside, the quiet was heavy.

Mark sat with his hands resting flat against the table. They were the hands of a man in his early fifties who had spent nearly three decades in enterprise operations, hands that had once handled thick manila folders, marked up blueprints with red ink, and signed off on customs manifests across five regional shipping hubs.

“I thought I was building an ironclad moat,” he told me, his voice carrying the dry, matter-of-fact register of someone reading a post-mortem report on his own career. “I spent two years listening to every webinar, every tech podcast, every executive mandate telling us that AI wouldn’t replace managers, but managers who knew how to use AI would replace those who didn’t. So I took the bait. I learned the toolchains. I built autonomous agents. I turned myself into the sharpest conduit in the firm.”

He paused, glancing at his quiet phone.

“Last Tuesday, my desk was cleared. Not because I was lagging behind the technology, but because I succeeded in building a machine that didn’t need me to turn the crank.”

Over 25 years of reporting on labour transformations, technological upheavals, and the quiet casualties of modern industry, I have watched this pattern repeat itself under different names. In the late 1990s, when digital typesetting swept through legacy newsrooms, veteran compositors proudly taught software how to space lead type, convinced their mastery of kerning and layout logic would preserve their seniority. Within three years, the keyboards were gone, and a single desktop publisher did the work of 40 men. In the mid-2000s, when enterprise resource planning software swept corporate back-offices, logistics coordinators meticulously mapped their spreadsheets into databases, unwittingly writing the exact rulebook that rendered their coordination roles obsolete.

Every major wave of technological disruption dangles the same narcotic promise before the ambitious middle worker: Become the multiplier.

It sounds like empowerment. It flatters the ego. It suggests that by strapping an algorithmic jetpack to your back, you will become indispensable to an executive floor that has spent its entire history looking for ways to trim overhead.

Mark was the poster child of that promise. As regional operations lead for a Singapore-based supply chain company, his entire job used to be a weekly crucible of human friction. Every Monday, country managers from Jakarta, Manila, Bangkok, and Port Klang sent through 30-page performance updates: messy, defensive, uneven dossiers filled with contradictory data and unresolved interpersonal squabbles between warehouse teams and local couriers.

Mark’s entire value had once resided in his ability to read between those lines. He knew who was bluffing about vehicle maintenance, who was hiding margin decay, and whose family crisis was bleeding into depot turnaround times. He spent his Sundays in messy, uncomfortable back-and-forth calls, asking awkward questions, steadying anxious nerves, and hammering out a realistic picture of the week ahead.

Also Read: Southeast Asia is counting what it automated, it is not counting what came back

Then came the mandate to optimise.

Mark threw himself into building an agentic workflow. He strung together document-parsing scripts, language models, and automated reporting hooks. The incoming PDFs were ingested in seconds; anomaly detection routines flagged inventory variances; auto-prompted sub-agents drafted clean, bulleted executive briefs categorised by risk severity. The cycle time collapsed from 14 exhausting hours to under four minutes.

His European managing director was ecstatic. Mark was invited to present his automated setup at an all-hands leadership offsite. He was hailed as the model operator of the AI era.

“I felt invincible,” Mark told me. “My calendar opened up. I had zero unread emails. My reports were pristine, free of typos, mathematically airtight. Every Monday at 8:00 AM sharp, the C-suite received a synthesis that looked like it had been compiled by a team of McKinsey consultants.”

What Mark did not see was that in engineering out the friction, he had quietly engineered out his own soul.

The fundamental problem facing knowledge workers and managers today is not that artificial intelligence is becoming sentient; it is that human beings are actively stripping away their humanity to mimic the speed and detachment of software.

When you spend your days orchestrating automated outputs, you inevitably anchor your worth to process and delivery. But process is precisely what code is written to swallow. By converting messy human operational dilemmas into neat, deterministic summaries, Mark wasn’t displaying rare intellect; he was merely standardising an operational pipeline.

He had turned his role into an API. And once a role becomes an API, leadership does not need a well-compensated veteran director sitting in the loop to press “Run.” A junior coordinator at a fraction of the cost, or an automated cloud trigger, can execute the identical prompt.

The cracks appeared long before his dismissal, though Mark had been too intoxicated by his dashboards to notice.

“Tell me about the last real dispute you handled,” I asked him.

He looked down at the table, his brow furrowing. “A depot head in Johor Bahru. Our throughput scores began slipping in the third quarter of last year. In the past, I would have driven up across the causeway, taken him out for bak kut teh, and figured out what had broken in the depot culture. But the agentic pipeline had already diagnosed the issue: shift delays, courier routing bottlenecks, mechanical downtime. The system auto-drafted a performance remediation notice based on regional HR protocols. I reviewed the bullet points, thought the logic was flawless, and authorised the send.”

He let out a short, bitter breath.

“He resigned 72 hours later. Took his three best shift supervisors with him. The entire depot stalled for almost a month. What the system didn’t know (what I never found out because I never picked up the phone) was that the man’s wife had been admitted to intensive care, and his team had been quietly covering his night shifts so he could sleep by her hospital bed. The automated notice landed like a slap in the face. It was completely logical, completely defensible, and utterly destructive.”

The algorithm had extracted every metric, but it was stone-deaf to the subtext of human loyalty.

Also Read: The AI told me to raise my prices by 40 percent but it had never been to a wet market

When organisations rely entirely on frictionless automation, they mistake the volume and polish of output for actual health. They produce immaculate spreadsheets while the social fabric of the company rots from within. Because an AI model operates strictly on consensus (on the average of historical patterns), it can only ever produce the standard, predictable playbook. It cannot exercise taste. It cannot sense fear in a pregnant pause during a video call. It cannot take an irrational, high-stakes bet on a struggling colleague based on an unquantifiable gut feeling.

The turning point for Mark came six weeks ago, inside the very boardroom where he had once demonstrated his agent workflows.

The managing director sat across from him with the quarterly financial projections. The tone was polite, professional, and entirely devoid of malice. The company was facing regional margin pressure. They were streamlining the operational layer. The automated pipeline Mark had built was running smoothly; it was now maintained by an entry-level technical specialist who cost one-third of Mark’s salary.

“They didn’t push me out because the machine failed,” Mark said. “They pushed me out because I had spent 18 months proving that my role was just an automated sequence of prompts and approvals. I had made myself redundant by acting like the very tool meant to serve me.”

That is the quiet crisis looming over the modern knowledge economy. If your day-to-day value can be reduced to pulling data, formatting updates, synthesising memos, and routing tasks, you are not upskilling. You are documenting your own retirement.

The real insight of the automation age is counterintuitive: the competitive moat has nothing to do with execution speed. Execution is rapidly approaching zero cost. When any intern with access to an agent stack can draft a 40-page strategy memo or generate a financial analysis in minutes, the value of the document itself plummets.

What becomes infinitely scarce, and therefore infinitely valuable, is the messy human edge that no script can synthesise:

The moral courage to reject the statistically probable scenario because your intuition tells you the ground has shifted.
The relational presence to endure an awkward, unscripted silence on a phone call until an anxious team member finally tells you the truth.
The accountability to stand before executive leadership, point to an unhedged decision, and say: “The dashboard says otherwise, but I own this outcome if it fails.”

An AI model can offer probabilities; only a human being can assume risk. An AI model can summarise speech; only a human being can listen with empathy.

Before we left the café, I asked Mark what advice he would give to the thousands of professionals currently scrambling to add autonomous agents and prompt workflows to their daily routines.

He adjusted his glasses and looked toward the sunlit street outside.

“Use the tools to sweep the floor,” he said, his voice quiet but steady. “Let them clean the data. Let them format the slides. Let them process the administrative garbage that eats your daylight. But never mistake that for your purpose.”

His parting words were a challenge to anyone currently building an automated workflow:

“Keep your hands firmly on the steering wheel. Refuse the shortcut when trust is at stake. When a decision is hard, step away from the terminal and walk into the friction. Because if you spend your career trying to out-calculate the computer, the computer will eventually take your chair. Your human edge isn’t the machine you operate. Your human edge is you.”

—

Editor’s note: e27 aims to foster thought leadership by publishing views from the community. You can also share your perspective by submitting an article, video, podcast, or infographic.

The views expressed in this article are those of the author and do not necessarily reflect the official policy or position of e27.

Join us on WhatsApp, Instagram, Facebook, X, and LinkedIn to stay connected.

The post The ghost in the middle: How one manager upskilled himself out of the room appeared first on e27.

Posted on — Leave a comment

Fear is high and longs got flushed. Is US$70,000 the next line in the sand?

My point of view is straightforward. The recent Bitcoin drop looks like a macro-led repricing with a leverage amplifier, not a Bitcoin-only failure. Bitcoin fell 3.45 per cent to US$71,425.63 in 24 hours and traded near a reported 12-week low. The broader crypto market fell 2.66 per cent to US$2.39 trillion. Bitcoin underperformed the wider market and became the main drag. 

The primary force came from higher US yields. A market recap on November 12 said hotter inflation pushed the US 10-year yield above five per cent as traders priced in more Fed hikes. That recap put Bitcoin down 4.3 per cent near US$71,400. The TLDR snapshot put Bitcoin down 3.45 per cent to US$71,425.63. The 2 snapshots differ slightly, and they point in the same direction. Higher yields can make speculative assets less attractive.

Bitcoin’s outsized decline pulled the wider crypto market lower. Markets reacted to Nvidia CEO Jensen Huang’s reported departure and uncertainty about potential selling tied to Strategy’s planned MSCI index removal. Those items remain reported market concerns, not proof of a single cause. 

The secondary force came from liquidations. Bitcoin long liquidations reached US$252.84 million in 24 hours, up sharply from the prior period. Forced closures can add sell orders and deepen a decline. Liquidation data reflects and amplifies selling pressure. It does not establish the original cause. Market sentiment remained fearful, and major crypto sectors were down.

That broad weakness supports the view that selling spread beyond Bitcoin. I treat the liquidation figure as evidence of leverage stress. The root cause looks more like higher yields and a market-wide move away from speculative assets. That distinction matters for the near term. A leverage flush can end once forced positions clear. A macro repricing can last longer if yields keep pressing speculative assets.

Also Read: Is short covering the only reason Bitcoin moved higher?

The 97 per cent correlation with Gold strengthens my macro-first reading. A strong correlation between crypto and Gold indicates a shared macro repricing. I do not take that correlation as proof of causation, and I would not overstate it. It weakens the case for a Bitcoin-only narrative. If Bitcoin and Gold move together under yield pressure, the more reasonable explanation is a common macro driver, not a crypto-specific event.

That is why I see the Nvidia and Strategy headlines as reported concerns that added uncertainty. They did not serve as confirmed triggers. The market recap put Bitcoin down 4.3 per cent near US$71,400, and the broader crypto market fell 2.66 per cent, so Bitcoin’s drop was a larger force in the move. The market-wide weakness also tells me that traders reduced risk across crypto.

Near-term momentum looks weak. Bitcoin sits below the US$73,936 daily pivot, and the reported 24-hour low was around US$71,200. If Bitcoin holds near US$71,200, it could attempt a rebound toward the pivot. A break below US$70,000 risks extending losses. The total crypto market cap sits at US$2.39 trillion, which is also the stated pivot level.

If the market cap holds near US$2.39 trillion and Bitcoin stabilises, losses could ease. Continued yield pressure or a break below that level would keep downside risk elevated. I would watch whether Bitcoin selling and long liquidations cool. I would not treat oversold readings alone as proof of a bottom. Stabilisation needs demand and calmer leverage.

Also Read: CPI at 0.4% broke Bitcoin’s US$73,000 floor. What happens if the Fed goes bigger?

The next daily US spot Bitcoin ETF flow report is a useful demand check. If flows improve and the market holds US$2.39 trillion, selling pressure could fade. If flows stay weak alongside continued yield pressure, the outlook weakens. I also mark Strategy’s planned MSCI index removal on November 30, 2026 as a future watch item. The available material does not confirm a Bitcoin sale tied to that change. The potential selling impact remains uncertain.

Any confirmed flows around the November 30 index change would matter more than headlines. The Nvidia CEO departure concern and the Strategy index concern both sit in the reported-concern category. They do not sit in the confirmed-catalyst category. I would keep that distinction clear when judging the next move.

My conclusion is that bearish pressure persists. Market-wide weakness and heavy long liquidations help explain the drop. The available evidence does not establish 1 definitive catalyst. The key watch over the next 24 to 48 hours is whether Bitcoin can hold above US$71,200 and recover the US$73,936 pivot. 

—

Editor’s note: e27 aims to foster thought leadership by publishing views from the community. You can also share your perspective by submitting an article, video, podcast, or infographic.

The views expressed in this article are those of the author and do not necessarily reflect the official policy or position of e27.

Join us on WhatsApp, Instagram, Facebook, X, and LinkedIn to stay connected.

The post Fear is high and longs got flushed. Is US$70,000 the next line in the sand? appeared first on e27.

Posted on — Leave a comment

The AI draft is the easy part. The source check is the job

In corporate communications, the first useful thing an AI assistant does is not write a finished announcement. It gives you a place to begin. It can turn a long technical brief into an organised list of claims, flag missing stakeholders, or reconstruct a scattered email chain into a timeline that people can check.

That speed is useful. But a clean summary can still be wrong in the way that matters most: it can make an exploratory conversation sound like an approved contract, an old quote sound current, or a possible roadmap sound like a commitment. The prose may be fluent while the status is false.

I treat generative models as drafting and triage tools, never as the source of record. Before a sentence leaves my desk, I want clear answers to three questions: What exactly are we claiming? What source supports it? What is its legal and commercial status?

Start with structure, not a paragraph

A communications brief is rarely a clean set of approved facts. It may combine verified information, market commentary, open decisions, and aspirational language. If you ask a model to write an announcement immediately, it may smooth those categories into one convincing paragraph. Uncertainty disappears from the prose even when it has not disappeared from the underlying evidence.

I get a better first pass by asking the model to act as a parser. It extracts each assertion into a table with the claim, its supporting document, the document’s author or owner, and whether written clearance exists. That changes the task from “make this sound exciting” to “show me what we can prove.”

The model can help identify missing sources, inconsistent dates, and repetitive language. A person still has to decide whether a claim is accurate, approved, and appropriate for public release. A polished draft can create pressure to send; a visible list of open checks makes it easier to pause.

Also Read: Open code, unowned risk: The governance gap in business-critical email

Audit the verbs of commitment

In corporate communications, verbs such as “launched,” “partnered,” “selected,” “acquired,” and “secured” carry weight. They describe different states of affairs. A model that treats them as stylistic variations can turn an exploratory discussion into an announcement of a completed relationship.

An AI-assisted draft can draw on genuine historical correspondence and recast it as a current partnership. The source material may exist; the implication may not. The fix is not another prompt. It is to return to the primary correspondence, check the relevant agreement and approvals, and remove the unsupported assertion.

That discipline applies to Votee AI’s own communications too. The HKMA’s published list names Votee AI among the technology partners selected for the first GenA.I. Sandbox++ cohort; the SFC’s published annex records the same cohort. Similarly, our CTO is listed as a contributor to OWASP’s Agentic Skills Top 10 (AST10), a framework documenting security risks in AI agent skills.  “Selected” and “contributed” are different claims, and each should match exactly what the public record shows.

The governance question for agents

The industry is moving from scripted chatbots towards systems that can plan and use tools across multiple steps. That can make software more capable, but it also makes permissions, oversight, and accountability harder to reason about.

An agent with access to company data should not be treated as safe simply because its output sounds plausible. Systems need limits on what an agent can access and do, clear records of the actions it takes, and a way for people to review or stop consequential steps. A practical “maker-checker” approach can help: one component gathers information or prepares a draft, while a separate control process checks the action against defined rules and routes higher-risk decisions to a person.

Also Read: AI is a tool. Stop treating it like a strategy

Review should scale with risk. An internal recap email does not need the same scrutiny as a public statement, a regulatory filing, or an earnings disclosure. But each process should make clear which facts are verified, who approved them, and what remains uncertain.

Use saved time to check the record

The useful promise of AI in communications is not that it removes human judgement. It is that it can reduce the manual work of sorting, collating, and summarising information from different documents.

The important question is what we do with the time saved. I use it to trace claims to their sources, ask subject-matter colleagues what a document actually authorises, and check whether a draft reflects the decision that was made, not merely the decision someone hopes will be made.

A strong draft is not the one that sounds most certain. It is the one whose confidence matches the evidence behind it. In communications, the source check is not a final proofreading step. It is part of the work.

—

Editor’s note: e27 aims to foster thought leadership by publishing views from the community. You can also share your perspective by submitting an article, video, podcast, or infographic.

The views expressed in this article are those of the author and do not necessarily reflect the official policy or position of e27.

Join us on WhatsApp, Instagram, Facebook, X, and LinkedIn to stay connected.

The post The AI draft is the easy part. The source check is the job appeared first on e27.